

Top 6 Lenders for Long-Term Personal Loans in 2026
Last updated: 2026-10-17
Hunting for a lender that supports a twelve-year repayment window is a bit like looking for a needle in a haystack. Most standard personal loans stop their clocks at seven years, leaving anyone needing long-term flexibility in a tight spot. If you want to spread out payments to keep your monthly costs manageable, you have to look beyond “quick cash” providers.
You will likely need an institution that understands long-term debt restructuring or large-scale asset financing. Selecting the right partner involves more than just glancing at a single interest rate. You have to weigh how fast you get the money against the total interest you will pay over a decade.
A loan with a lower monthly payment over 144 months might look attractive on paper. However, once you run the math, you might find you are paying nearly double the principal in interest alone. This list looks at the top contenders to help you manage the complexities of long-term borrowing without falling into a debt trap.
- U.S. Bank
- Wells Fargo
- JetzLoan
- Citi
- OneMain Financial
- Alliant Credit Union
How These Lenders Were Evaluated
The evaluation process focused on availability, flexibility, and the ability to handle extended durations. Since most traditional banks cap terms at 84 months, the search prioritized lenders known for versatility. We examined how these companies handle the application process and the speed at which they distribute cash. We also looked at their reputation regarding transparency in fee structures.
We specifically looked for lenders that do not penalize borrowers for making extra payments. This is the most effective way to mitigate the long-term interest costs associated with extended repayment windows. Reliability and accessibility were the other major pillars of this comparison. A lender might offer a great rate, but if they require a mountain of paperwork or a week of waiting, they lose points.
We looked for a balance between institutional stability and modern, digital-first convenience to ensure a well-rounded list for various borrower needs. We also accounted for “hidden” variables, such as the difference between APR (Annual Percentage Rate) and the base interest rate. This ensures that recommendations prioritize the actual cost of borrowing.
| Lender | Max Loan Amount | Term Range | Funding Speed | Credit Check Type |
|---|---|---|---|---|
| U.S. Bank | see site | see site | see site | see site |
| Wells Fargo | $100,000 | 12-84 months | see site | see site |
| JetzLoan | $50,000 | see site | 24 hours | No hard pull |
| Citi | $30,000 | 12-60 months | see site | see site |
| OneMain Financial | $30,000 | 24-60 months | 1 hour | see site |
| Alliant Credit Union | see site | see site | see site | see site |
The Best Long-Term Personal Loan Options
1. U.S. Bank
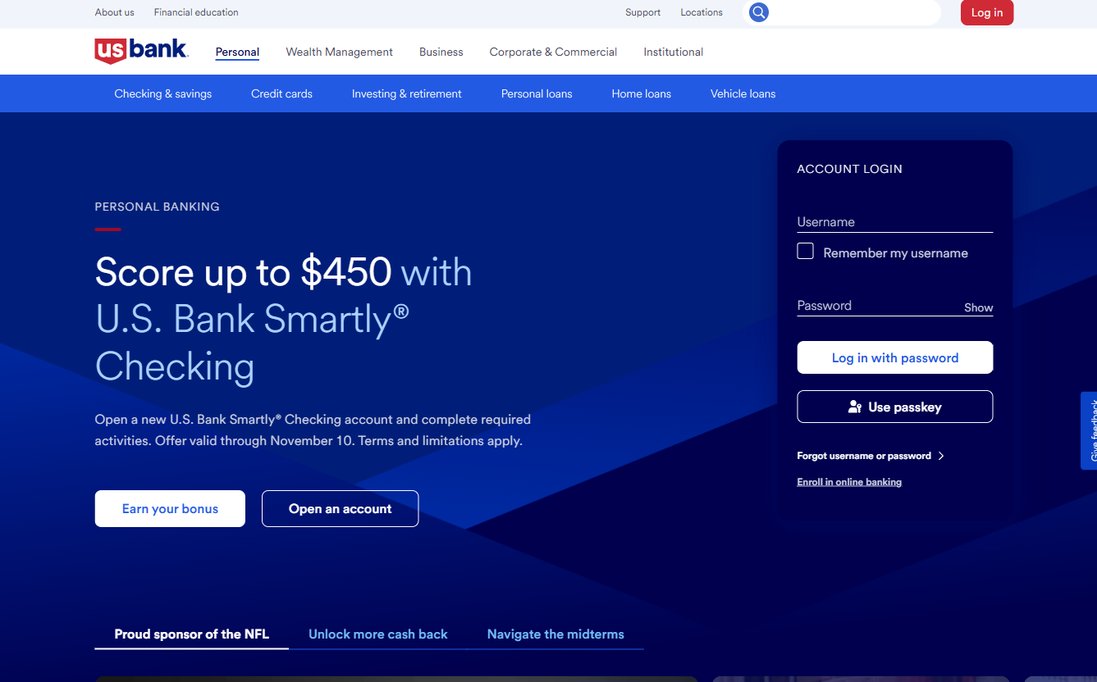
This institution remains a titan in the banking world, offering a comprehensive suite of services. For those seeking a personal loan, they provide a structured environment where you can manage your checking, savings, and loans all under one roof. It is a powerhouse for those who prefer a traditional banking relationship.
Their interface is designed for high-net-worth individuals and long-term planners who value the cohesion of a single institution. The loan products are designed for stability, which is essential when you are looking at long-term debt. If you already have a relationship with a large bank, the convenience of having everything in one dashboard can be a massive advantage for your monthly budgeting.
For instance, setting up an automatic transfer from your checking account to cover your loan payment is simple. This reduces the risk of accidental late fees, which can be devastating over a decade-long term. It is a solid choice for someone who wants everything in one place.
Pros:
- Integrated banking ecosystem for easy management.
- Wide variety of financial products including investing.
- Established institutional reputation.
Cons:
- May require more documentation than digital-only lenders.
2. Wells Fargo
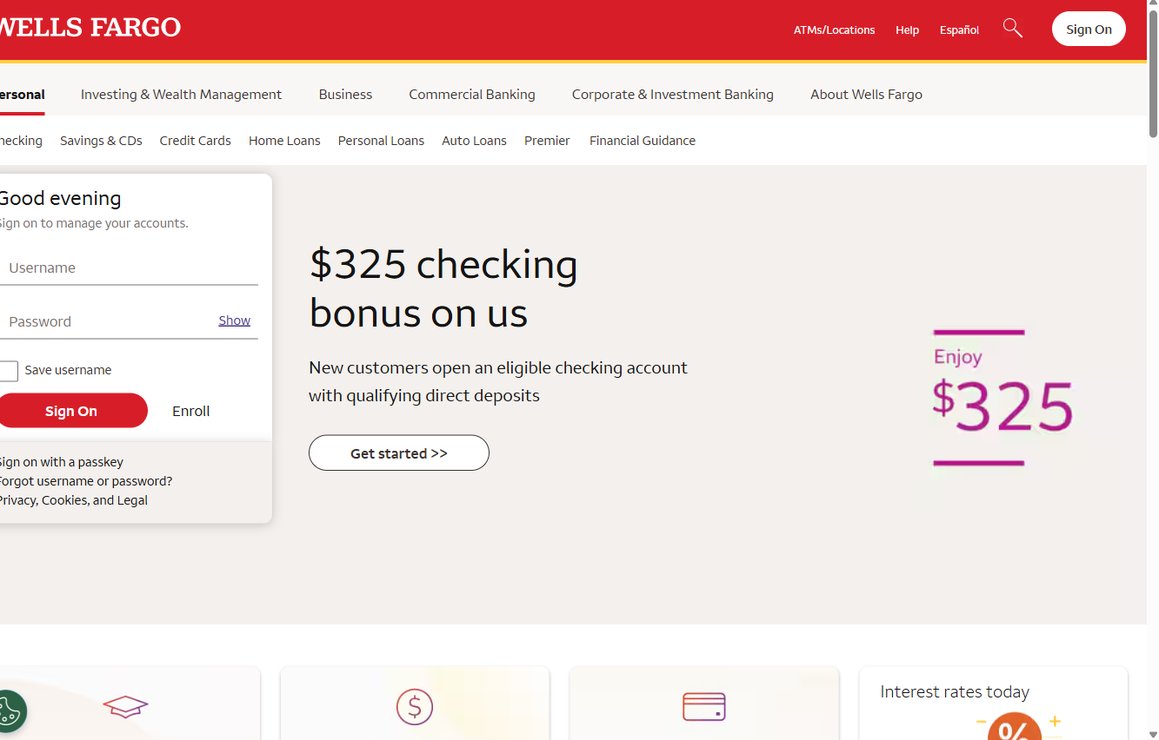
Wells Fargo is a heavy hitter when it comes to high-limit personal loans. If you are looking to tackle a major life event, such as a home renovation or a significant debt consolidation, their ability to provide up to $100,000 is hard to ignore. They offer a very competitive starting rate to attract serious borrowers, particularly those with established credit histories.
This makes them a primary choice for large-scale projects that require significant capital upfront. The predictability of their fixed interest rates is a lifesaver for anyone planning their finances years in advance. You won’t have to wake up one morning to find your monthly payment has spiked due to market volatility.
This provides a sense of security that is vital for long-term planning. When comparing them to variable-rate lenders, the “peace of mind” factor of a fixed rate often outweighs the slightly higher initial rate offered by more aggressive, risk-prone lenders. It is about knowing exactly what you owe every single month.
Pros:
- High maximum loan amounts up to $100,000.
- Fixed interest rates provide long-term predictability.
- Extensive branch network for in-person support.
Cons:
- High loan amounts may require excellent credit.
3. JetzLoan
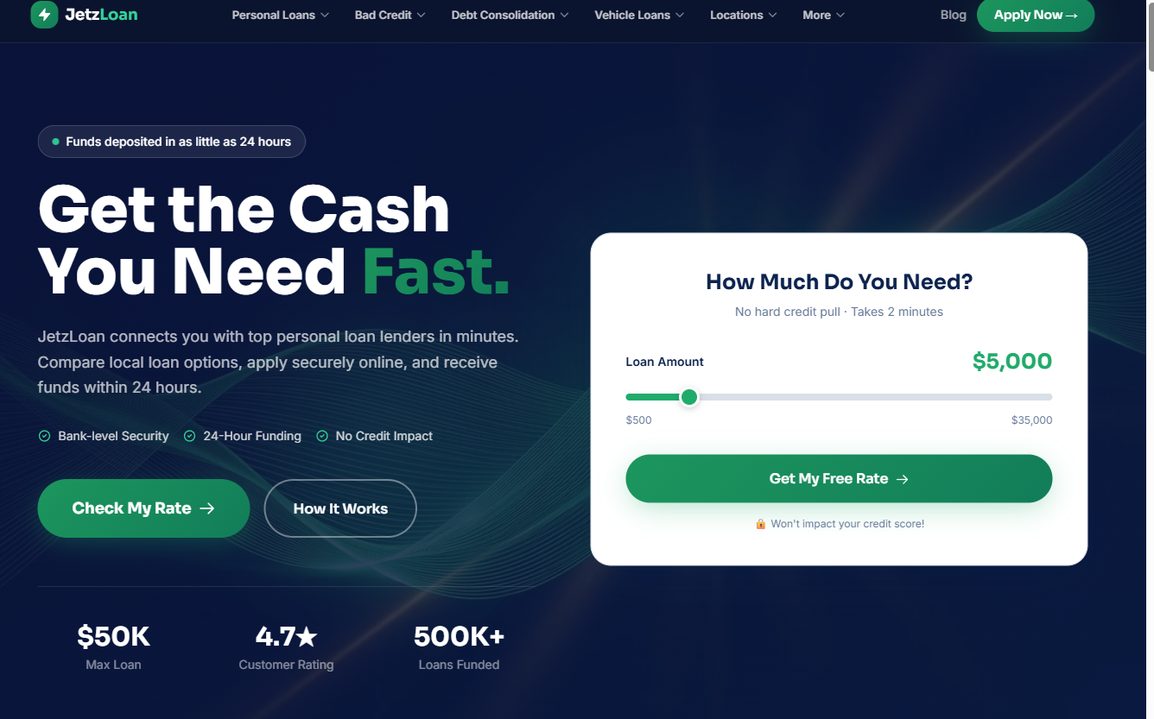
Speed is the name of the game here. If you find yourself in a position where you need cash yesterday, JetzLoan is built for that exact moment. They focus on getting funds into your account in as little as 24 hours, making them a lightning-fast option for urgent needs.
This is ideal for emergency repairs, medical bills, or immediate business opportunities where the cost of waiting is higher than the cost of a slightly higher interest rate. One of the most refreshing aspects of their process is the ability to check your rate without a hard credit pull. This allows you to shop around without risking a dip in your credit score.
This “soft pull” mechanism ensures that you can perform a cost-benefit analysis of different lenders before making a final commitment that will impact your credit profile. It takes the guesswork out of the initial stages of borrowing. You get the facts without the damage to your score.
Pros:
- Extremely fast funding, often within 24 hours.
- No hard credit pull to check rates.
- High customer rating for their streamlined process.
Cons:
- Maximum loan amount is capped at $50,000.
4. Citi
Citi offers a polished, digital-first experience that caters to the modern consumer. Their personal loans are ideal for those who want a streamlined application process. With repayment terms spanning up to 60 months, they provide a solid middle ground for many mid-term financial goals.
Their mobile app is frequently cited as a benchmark for user experience. This allows for easy tracking of principal reduction and interest paid. They are particularly well-suited for people who want to manage their finances through a sophisticated online interface. While they may not offer the extreme twelve-year stretches found in some niche markets, their structure is incredibly efficient.
If your goal is to consolidate high-interest credit card debt into a more manageable 5-year plan, Citi is a top-tier candidate. It is a great option for someone who wants a smooth, digital experience without needing a decade-long commitment. Their interface makes the math very easy to see.
Pros:
- Excellent digital banking and online interface.
- Well-structured repayment terms up to 60 months.
- Strong reputation for managing high-limit credit.
Cons:
- Maximum term is 60 months, not 12 years.
5. OneMain Financial
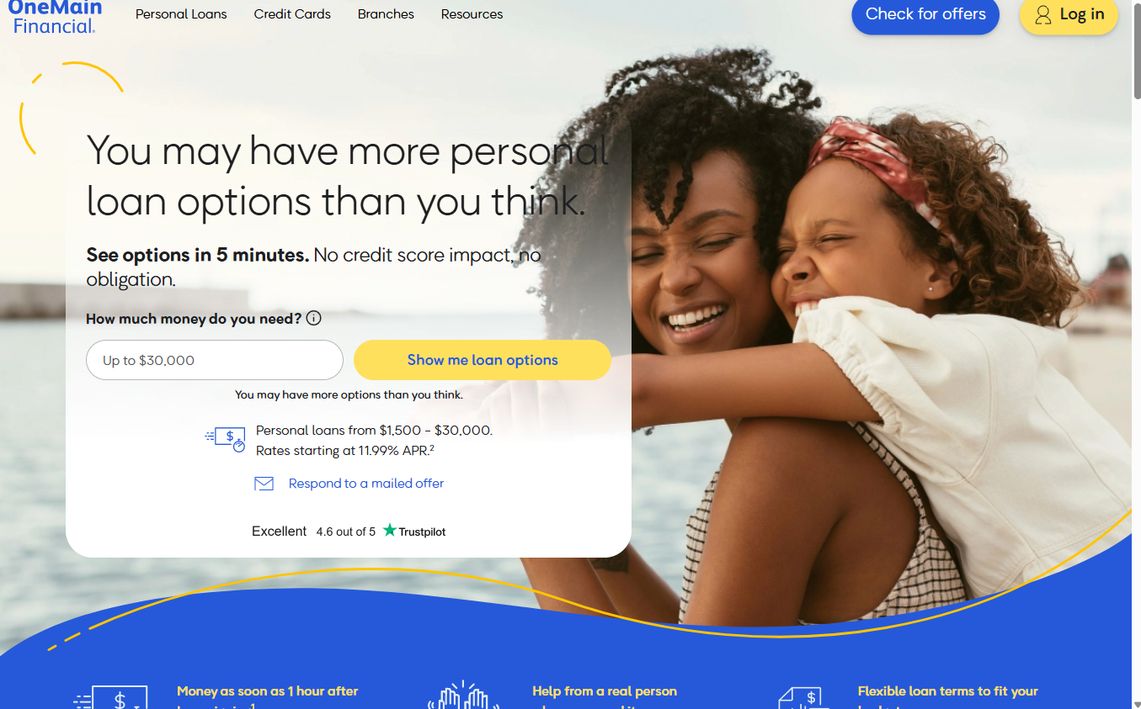
If you feel like the big banks have turned their noses up at you, OneMain Financial might be your best bet. They specialize in providing options to people who might have a less-than-perfect credit history. Their ability to get you money as soon as one hour after signing is legendary.
They focus on the individual’s current ability to repay rather than just a static credit score, making them a vital resource for those in transition. They lean heavily into the human element of banking, with a massive network of over 1,300 branches. This means that if you run into a snag, you can actually walk into a building and talk to a real person.
This is much better than shouting at a chatbot when things get complicated. This physical presence provides a layer of accountability and support that digital-only fintechs simply cannot replicate, especially when navigating complex loan terms. It offers a sense of stability when you are in a tough spot.
Pros:
- Extremely fast funding, potentially in one hour.
- Large physical presence with 1,300+ branches.
- Accessible for those with non-standard credit.
Cons:
- Interest rates can be higher for some borrowers.
6. Alliant Credit Union
Credit unions often offer a different flavor of banking, and Alliant is no exception. Because they are member-owned, their focus often shifts toward providing better rates and more benefits to their members. Their high-rate savings and checking accounts make them a great place to park your money.
This member-centric model often results in lower fees compared to the “Big Four” national banks. While they are a powerhouse for savings and certificates, their loan products are part of a broader ecosystem. They are an excellent choice for those who want their money to work harder through higher interest yields.
For a borrower looking to build long-term wealth while managing existing debt, the Alliant ecosystem provides a holistic approach to personal finance. It is a smart play for those who want to stay within a community-focused financial environment. You get quality credit products alongside strong savings tools.
Pros:
- Member-owned structure often leads to better rates.
- High-yield savings and checking options.
- Excellent digital banking improvements.
Cons:
- Membership requirements may apply.
The Hidden Costs of Long-Term Debt
When you extend a loan to its maximum duration, you are essentially trading monthly cash flow for total interest expense. It is vital to understand the math behind this trade-off. For example, consider a $20,000 loan. At a 10% interest rate, a 5-year term results in roughly $5,500 in total interest.
However, if you stretch that same $20,000 out to 10 years, even at the same 10% rate, you will pay approximately $11,700 in interest. You have doubled your monthly comfort but more than doubled your total cost. Understanding the “Effective Cost of Borrowing” is essential to avoid being blindsided by the numbers later on.
This includes several specific factors to watch for:
- Origination Fees: Some lenders charge a percentage of the total loan (often 1-8%) just for processing the application. This is taken out of your initial funds, meaning you receive less than the amount you actually owe.
- Prepayment Penalties: Many long-term loans include clauses that charge you a fee if you pay the loan off early. This is because the lender loses out on the interest they expected to collect from you. Always prioritize lenders that allow “penalty-free” early repayment.
- Late Fees and Compounding Interest: In a 12-year term, a single missed payment or a short delay can trigger compounding interest. You end up paying interest on your interest. This can cause the principal to stagnate or even grow.
How to Navigate Long-Term Borrowing
Before you sign on the dotted line, you must realize that a twelve-year loan is a massive commitment. While the monthly payments might look tiny, the total interest you pay over a decade can be staggering. It is like a marathon; you need to ensure you have the stamina to keep running for the full duration.
Your income, career stability, and cost of living will all change over twelve years, and you must plan for that volatility. Avoid the temptation to take the longest term just because you can. A longer term reduces your immediate monthly burden, but it increases the total cost of the loan significantly. If you can afford to pay more each month, you will save thousands of dollars in the long run.
A common strategy is to take the long term to ensure you can always meet the minimum payment, but to aggressively pay extra whenever you receive a bonus, tax refund, or raise. This gives you the “safety net” of a low monthly requirement with the “wealth-building” benefit of a short-term loan. It is about having flexibility when things are tight and speed when you have extra cash.
Watch out for hidden fees that can sneak into the contract. Always ask about prepayment penalties. If you come into some extra cash and want to pay off the loan early, you don’t want the bank to punish you for being responsible. Always read the fine print before you let anyone access your bank account.
Specifically, look for the phrase “all payments are applied first to interest and then to principal”—this is standard, but you want to ensure you can make extra payments that go directly toward the principal balance. This is the fastest way to accelerate your path to debt freedom and stop the interest from eating your income.