

Top 6 Lenders for Loans for the Unemployed with Bad Credit in 2026
Last updated: 2026-10-16
Losing a job feels like a heavy blow to the gut. Suddenly, you’re staring down a mountain of bills that don’t care about your employment status. When that steady paycheck vanishes, the stress of keeping a roof over your head can feel suffocating.
This isn’t just about changing your lifestyle; it’s about basic survival. From the rent due on the first to the utility bills that keep the lights on, the sudden lack of income threatens your core security. Finding a way to bridge that gap is a daunting task, often requiring a delicate balancing act between staying afloat today and maintaining some semblance of financial stability for tomorrow.
The situation gets even tougher if your credit history is anything less than perfect. Most traditional banks will turn their backs the moment they see a low score or a gap in your work history. To a standard lender, being unemployed looks like a massive risk of default. This often triggers an automatic rejection from their automated underwriting systems.
This list examines which lenders offer actual options for people navigating these specific, difficult financial waters throughout 2026.
- Avant
- Upgrade
- FastLendGo
- Wells Fargo
- NetCredit
- OneMain Financial
How These Lenders Were Evaluated
Picking a lender requires looking past the glossy advertisements. We focused on how fast you get the money and how flexible the application process actually is. For someone without a current job, being able to use alternative verification methods—like bank statements instead of traditional pay stubs—is a massive deal. It’s the difference between getting a loan and getting a rejection letter.
We checked how lenders verify income through third-party data aggregators. This can be a lifesaver if you are a freelancer or if your income is irregular. It moves the conversation away from “do you have a boss?” toward “can you actually pay this back?”
Transparency matters too. A lender might offer quick cash, but if the interest rates are predatory, you aren’t solving your problem; you’re just delaying it. A low monthly payment sounds great, but if the term is stretched to 72 months, you might end up paying back double what you borrowed. We looked for a balance between accessibility for bad credit and reasonable repayment structures.
| Lender Name | Loan Amounts | Terms/Rates | Funding Speed | Credit Requirements |
|---|---|---|---|---|
| Avant | See site | See site | See site | Bad Credit Options |
| Upgrade | Up to $50,000 | See site | Fast funding | See site |
| FastLendGo | $500 – $5,000+ | See site | Quick access | Bad/Fair/Good |
| Wells Fargo | See site | See site | See site | Traditional Requirements |
| NetCredit | Up to $10,000 | See site | Same-day available | Advanced Algorithms |
| OneMain Financial | $1,500 – $30,000 | From 11.99% APR | As soon as 1 hour | See site |
1. Avant
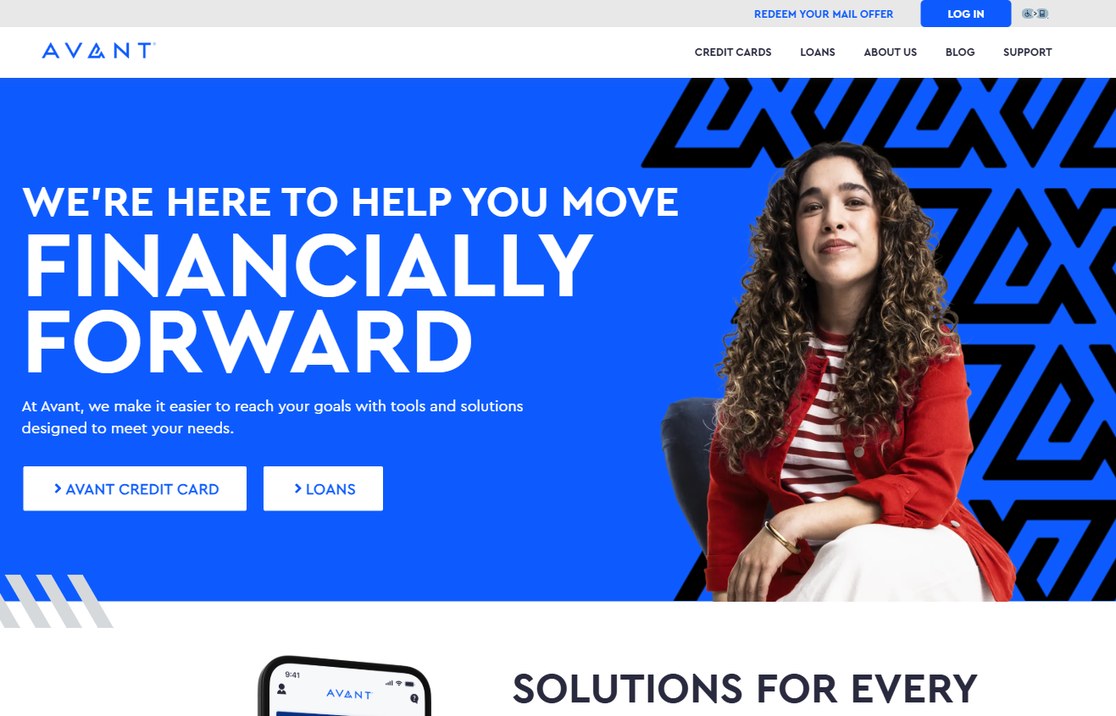
Avant tries to help people move forward even when life gets messy. They offer a variety of tools, including credit cards and installment loans, aimed at those needing a fresh start. Their approach works differently than the big banks. Instead of relying solely on rigid FICO scores, they use a proprietary model to look at a wider range of financial indicators.
This makes them a practical choice for debt consolidation or emergency funds. If you have a sudden car repair that might prevent you from getting to interviews, or if you just need to reorganize several debts into one monthly payment, their setup might work for you. It is a useful option for anyone moving between jobs or managing irregular income streams.
Pros:
- Flexible loan solutions for different needs
- Offers credit card options alongside loans
- Focuses on helping users move forward
- Specific interest rates not publicly listed in all contexts
2. Upgrade
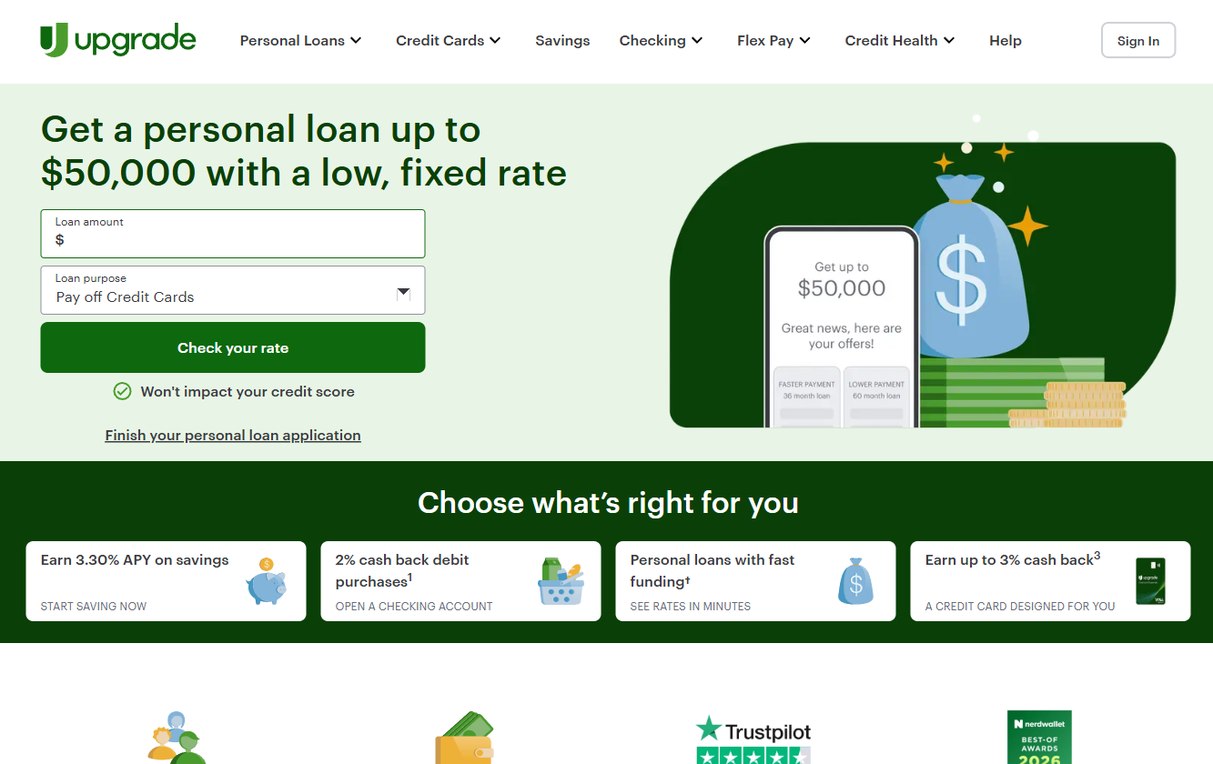
Upgrade is a major player in the personal loan market, with amounts going as high as $50,000. They cover everything from home improvements to large, one-time purchases. Their platform is built for speed. You can check your rates in just a few minutes without hurting your credit score because they use a “soft pull” for the initial check.
This “soft pull” is a lifesaver when you’re in a tight spot. It lets you shop around for the best terms without piling on more “hard inquiries” that tank your score. They also offer a checking account that gives cash back on debit purchases, making them a decent one-stop financial hub for many people.
If you need substantial capital to settle debts or fund a project, Upgrade offers a very streamlined experience. Since most of the process happens on a smartphone, it’s ideal for people who might not have easy access to a computer or a physical bank branch. It’s built for the digital age.
Pros:
- High loan amounts up to $50,000
- Fast rate checking with no credit impact
- Cash back rewards on checking accounts
- May require higher credit for the best rates
3. FastLendGo
FastLendGo works well for people needing quick cash for specific, immediate emergencies. They focus on smaller personal loans, starting as low as $500. This makes them a strong choice for things like dental bills, auto repairs, or a small utility deposit. Because the amounts are smaller, getting through the door is often easier than with a massive bank. (fastlendgo.com)
The service is designed for simplicity. You can quickly compare options online. Whether your credit is bad, fair, or good, they have a product tier that fits your specific situation. For instance, if you have a “fair” score but can show a history of consistent income, you might find better terms here than at a major institution.
It is a highly accessible option for someone in a pinch who needs a quick infusion of cash to stop a bad situation from getting worse. It’s about immediate relief for immediate problems.
Pros:
- Low entry point for small loans ($500)
- Covers specific needs like auto or dental
- Quick comparison of local options
- Small loan focus may not suit large debts
4. Wells Fargo
Wells Fargo is a massive, established institution. They offer a full suite of services, from checking accounts to home and auto loans. They are a cornerstone of the American banking system, providing a level of stability and a physical presence that many newer fintech companies simply cannot match.
However, if you are unemployed, getting a loan here is a steep uphill battle. Traditional banks typically demand documented proof of continuous employment for at least two years and a stable debt-to-income ratio. They aren’t usually looking to take risks on anyone without a steady, verifiable paycheck.
That said, their wide range of products makes them a great destination for rebuilding your financial health once you find a new job. If you already have an account with them, it’s worth asking a representative about hardship programs or temporary assistance. Sometimes, a human conversation can open doors that an algorithm will keep shut.
Pros:
- Extensive range of financial products
- Highly established and reputable institution
- Comprehensive wealth management options
- Tighter requirements for traditional loans
5. NetCredit
NetCredit operates on the idea that you are more than just a number in a database. They use advanced algorithms to look past a standard FICO score. This can be a lifeline for people with imperfect credit who still need significant financing. By looking at how you handle current utility bills or rent, they can see reliability that a credit report might miss.
With loan amounts up to $10,000 and options for same-day funding, they prioritize speed. Their application process is simple, making them an attractive option for covering urgent expenses or consolidating high-interest debt. It’s a common way to take multiple small, expensive credit card balances and turn them into one single, lower-interest monthly payment.
Pros:
- Uses advanced algorithms for underwriting
- Same-day funding availability
- Loans up to $10,000 available
- Subject to underwriting partner bank rules
6. OneMain Financial
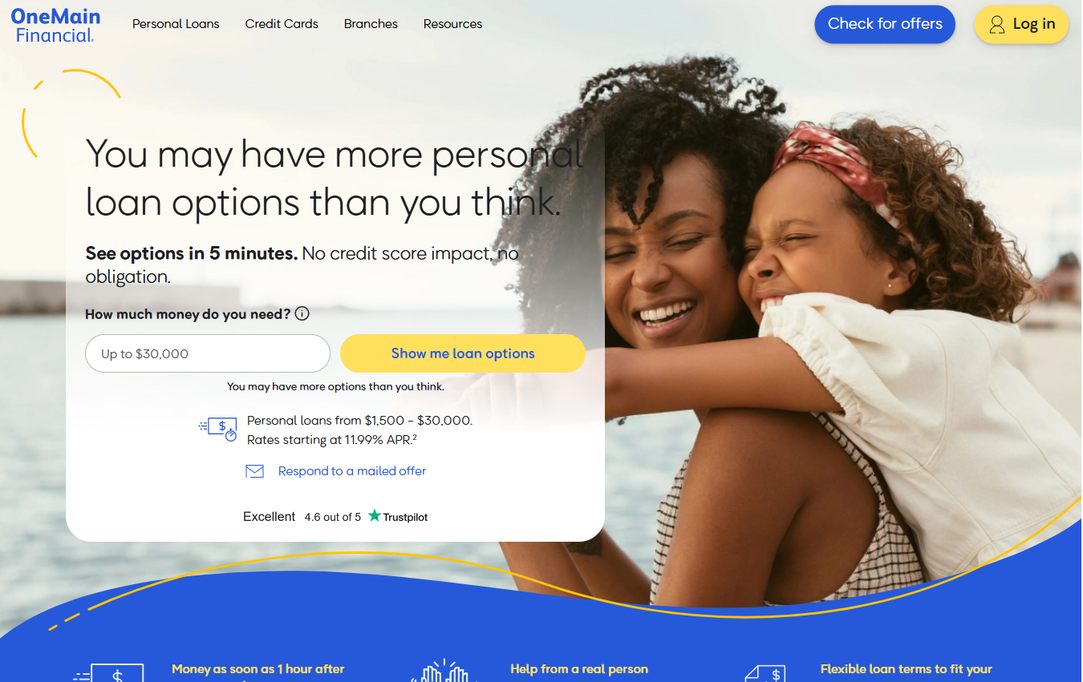
OneMain Financial is a great choice if you prefer talking to someone in person. They have about 1,300 branches across the country. They offer personal loans from $1,500 up to $30,000, with rates starting at 11.99% APR. Having a physical branch can be a huge comfort when you’re dealing with high-stress financial times.
One of their best features is how fast you can get the money. You can see funding as soon as one hour after signing the loan. This is perfect for an emergency, like a broken furnace or an urgent medical bill, where every hour counts. Being able to sit down with a loan officer to explain your specific situation provides a level of reassurance that a website can’t provide.
Pros:
- Very fast funding (as soon as 1 hour)
- Extensive branch network for in-person help
- Predictable fixed monthly payments
- Requires a loan signing process
Understanding the Real Cost of Borrowing
Before you sign anything, you must understand the difference between the APR (Annual Percentage Rate) and your monthly payment. The APR includes the interest rate and any mandatory fees. It is the only way to see the true cost of the loan. When you are in a crisis, you might focus only on the monthly payment, but a low payment can be a trap if the term is too long.
A $500 monthly payment sounds manageable. But if you’re paying that for five years, you’re paying back way more than you originally borrowed. It is an illusion of affordability that can lead to a debt trap.
Keep these three metrics in mind when you’re comparing offers:
- Total Cost of Loan: Multiply your monthly payment by the total number of months and add any upfront fees. This is the actual price of the money.
- Prepayment Penalties: If you get a new job and want to pay the loan off early to save on interest, check if there is a fee for doing so. Look for a “no prepayment penalty” clause.
- Origination Fees: Some lenders take a fee out of the loan before you even see it. If you borrow $1,000 but only get $950, your interest rate is actually higher than the number they quoted you.
Strategic Steps for Financial Recovery
If you use a loan to bridge the gap while you’re unemployed, treat it as a tool, not a lifestyle. Use the money for the essentials: housing, food, transportation, and utilities. Don’t use it to keep up appearances or maintain a lifestyle that your current income can’t support. The goal is to buy yourself enough time to find a job without drowning in high-interest debt.
While you navigate this period, follow these tactical steps to protect your credit and your sanity:
- Contact Your Current Creditors: If you can’t make a mortgage or car payment, call the lender *before* you miss the due date. Many have hardship or forbearance programs for exactly this reason.
- Prioritize “Survival” Expenses: If money is tight, pay your rent, utilities, and food first. Credit scores matter, but shelter and food come before credit card companies.
- Audit Your Subscriptions: It sounds small, but canceling a streaming service or a gym membership can save you $50 or $100 a month. That adds up when you’re on a lean budget.
- Document Everything: Keep a folder of every loan application, term, and email from lenders. If a dispute happens later, having a paper trail will be your best friend.
When you’re between jobs, every dollar counts. Mistakes can be incredibly expensive. Always read the fine print and look for the total cost of borrowing, not just the monthly payment. You don’t want to be trapped by high interest when you’re already struggling.
Resist the urge to take out several small loans from different places at once. That is a quick way to create a cycle of debt that is nearly impossible to escape. Instead, find one solution that addresses your most urgent need and has a repayment schedule that actually fits your reality.
If things get really difficult, remember there are resources beyond high-interest loans. Sometimes negotiating with your current creditors or looking into local assistance programs can provide more relief than taking on new debt. Always weigh the long-term impact of a loan against what you need right this second.