

The 4 Best Lenders for Manufactured Home Financing in 2026
Last updated: 2026-10-17
Finding a place to call home often feels like running a marathon through a thunderstorm. For many, that dream home is a manufactured residence, but walking into a traditional bank can feel like hitting a brick wall. If you have encountered a “no” from standard lenders, you are certainly not alone in this struggle.
The complexity of the manufactured housing sector means that the financing process is rarely a straight line. It is a labyrinth of varying regulations, property classifications, and lender appetites. You have to know exactly what you are looking at before you sign anything.
Selecting the right lender depends entirely on your unique financial footprint. Some buyers need high-speed cash for quick repairs, while others require specialized programs designed specifically for mobile homes. Navigating these waters requires knowing which institutions specialize in your specific credit profile and housing type.
For instance, if you are purchasing a home on leased land, your financing needs will differ vastly from someone who owns the land beneath a manufactured home. Understanding this distinction is the first step toward successful homeownership.
- FastLendGo
- Triad Financial Services
- Sound Community Bank
- Fannie Mae
Evaluating the 2026 Manufactured Home Lending Landscape
The criteria for this evaluation focus on specialized product availability and accessibility. A lender’s ability to look beyond a simple credit score is paramount in this niche market. We looked at how these providers handle various credit tiers, from high-income professionals to those rebuilding their financial lives.
In 2026, the landscape has shifted toward more data-driven underwriting. This means that a single mistake in your digital financial footprint can impact your eligibility across multiple platforms. It is no longer just about what a human loan officer thinks of your history.
We also weighed the importance of loan structure and speed. In a fast-moving real estate market, waiting weeks for an answer can kill a deal. Therefore, we prioritized lenders that offer clear paths for different borrower needs, whether that involves traditional mortgage backing or specialized chattel financing.
We specifically looked at the distinction between “chattel loans”—which treat the home as personal property—and “real property” loans, where the home and land are bundled together. The latter often offers lower interest rates but requires much stricter documentation and a higher credit threshold.
| Lender Name | Loan Types | Max Loan Amount | Min Credit Score | Key Feature |
|---|---|---|---|---|
| FastLendGo | Personal Loans | See site | See site | Quick access to cash |
| Triad Financial Services | Manufactured/Mobile | See site | See site | Specialized financing |
| Sound Community Bank | Manufactured Home | $350,000 | 640 | FDIC-Insured |
| Fannie Mae | Single-Family | See site | See site | Desktop Underwriter |
Understanding the Critical Distinction: Chattel vs. Real Property Loans
Before you begin your applications, you must understand the two primary ways manufactured homes are financed. This is the most frequent source of confusion for first-time buyers. If you don’t get this right, you might face significant delays in the closing process.
It is better to sort this out now rather than discovering a problem when you are ready to move in. The difference between these two loan types changes everything from your interest rate to how you pay the loan back.
What is a Chattel Loan?
A chattel loan is essentially a personal property loan. It is used when the manufactured home is considered a piece of personal property rather than real estate. This is most common when the home is located in a mobile home park where you lease the land from a park owner.
Because the home is not tied to land you own, the lender views the loan more like an auto loan or a high-end personal loan. These loans are often easier to qualify for if your credit is less than perfect. However, they typically carry higher interest rates and shorter repayment terms, such as 10 to 15 years rather than 30.
What is a Real Property Loan?
A real property loan is a traditional mortgage. This is only an option if the home is permanently affixed to land that you (or a co-borrower) own. In this scenario, the home and the land are combined into a single piece of real estate.
This is the “gold standard” for financing because it offers the lowest interest rates and the longest terms. However, the requirements are much more stringent. You will likely need a formal appraisal that accounts for both the structure and the land, and your credit score will need to meet the higher thresholds set by institutions like Sound Community Bank.
Top Ranked Lenders for Manufactured Home Financing
1. FastLendGo
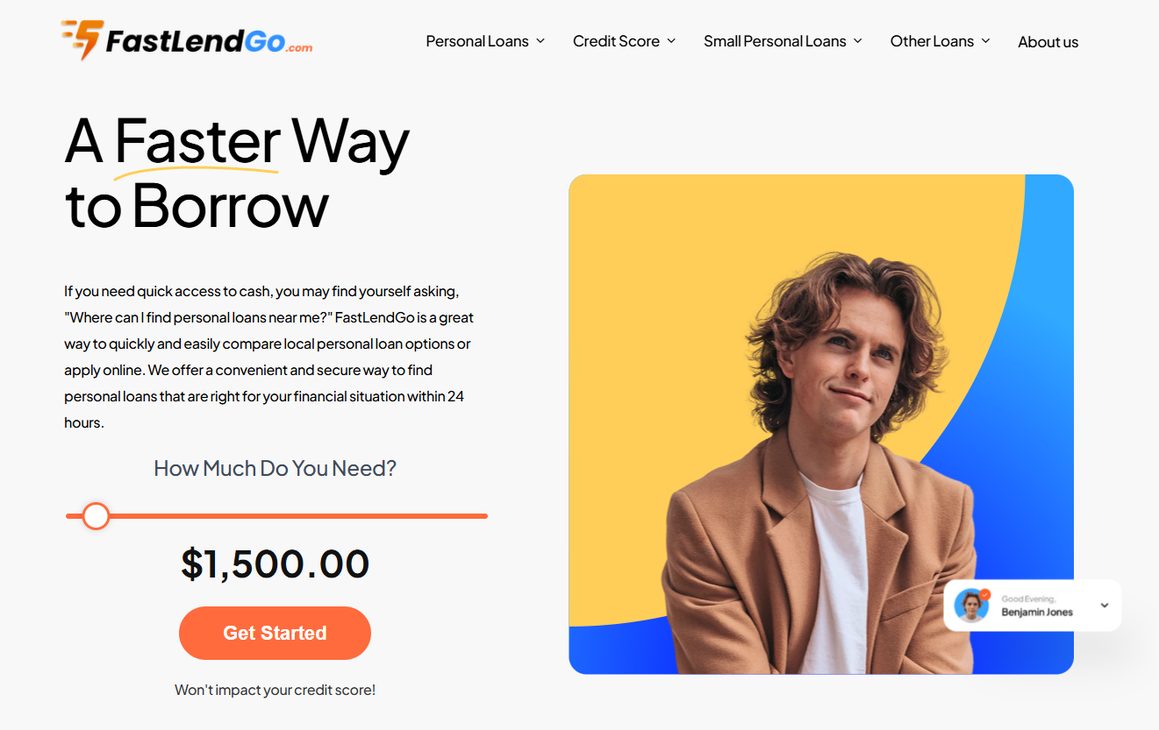
FastLendGo operates as a versatile partner for those needing quick access to cash. Instead of getting bogged down in the complexities of a mortgage, this provider focuses on personal loans that can be used for various needs. It is an ideal choice for those needing to bridge a financial gap quickly.
You might use this to cover the security deposit on a new property or to fund urgent structural repairs on a home you have just acquired. (fastlendgo.com)
This lender caters to a massive spectrum of borrowers. You might find yourself looking for a small $500 loan for an emergency or a larger $5,000 sum for a specific project. They offer tailored solutions for high-income individuals as well as those with less-than-perfect credit histories.
This flexibility makes them a valuable tool in a borrower’s “financial toolkit,” even if they aren’t your primary long-term mortgage provider.
Pros:
- Extremely fast access to cash for emergencies.
- Flexible loan amounts ranging from $500 to $5,000.
- Options available for various credit tiers.
Cons:
- Personal loan structures may differ from traditional home mortgages.
2. Triad Financial Services
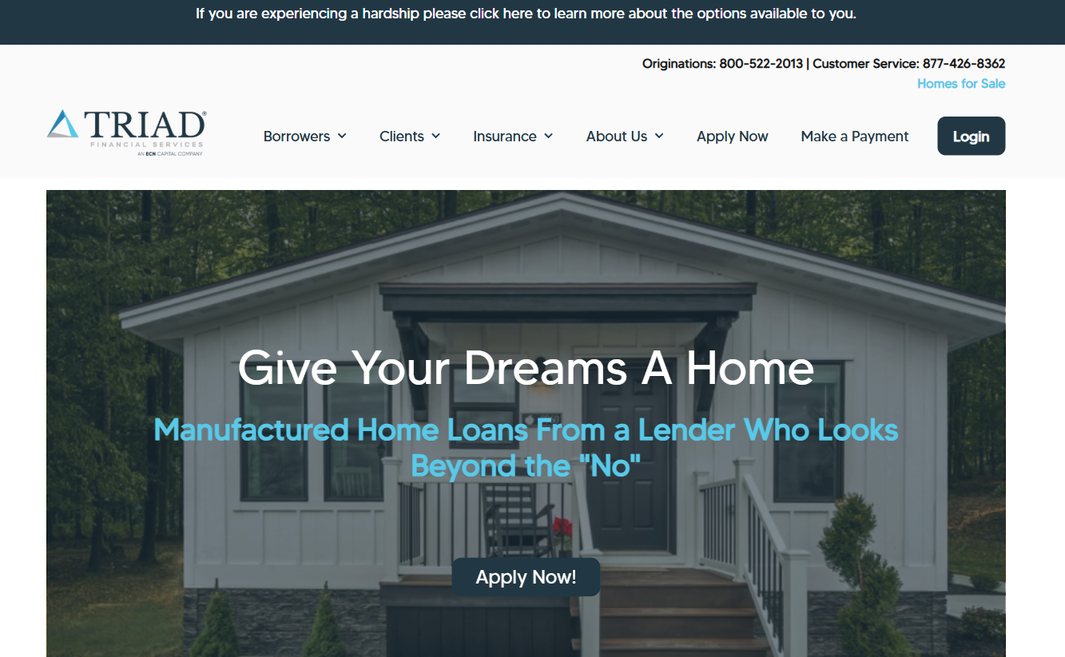
If you have been told “no” by traditional banks, Triad Financial Services might be the breath of fresh air you need. They specialize in what other lenders won’t touch, specifically manufactured and mobile homes. They have been in the game for over 65 years, providing stability in a volatile market.
Their longevity is a sign of their ability to handle the specific risks associated with manufactured housing. Many other lenders retreat when they see these specific property types, but Triad stays in the fight.
This lender is a specialist in the field of chattel loans. They understand the nuances of manufactured property better than a generalist bank. They know how to evaluate the depreciation of the structure and the specific ways that manufactured homes hold value differently than site-built homes.
If your goal is to secure a home despite a complicated financial past, their experience becomes an invaluable asset during the application process.
Pros:
- Decades of experience in specialized home financing.
- Focuses on manufactured homes where others hesitate.
- Designed for those facing financial hardships.
Cons:
- Specialized lending may come with different terms than standard mortgages.
3. Sound Community Bank
Sound Community Bank offers a more traditional banking experience for those purchasing manufactured homes. They provide structured loans with a clear set of requirements. This is a solid option for a buyer who has established their credit and wants the security of an FDIC-insured institution.
Working with a bank like this provides a sense of stability. Your funds are protected under the full faith and credit of the U.S. Government, which offers peace of mind during a major life transition.
The program includes specific parameters, such as a 10% minimum down payment and a minimum FICO score of 640. With loan amounts reaching up to $350,000, they provide a significant amount of breathing room for those looking to make a substantial investment in their property.
Because this is a “real property” style approach, it is highly recommended for those who intend to stay in their home for the long term and want to build equity through traditional means.
Pros:
- FDIC-insured with the full faith of the U.S. Government.
- Substantial loan amounts up to $350,000.
- Clear, predictable lending criteria.
Cons:
- Requires a minimum credit score of 640.
4. Fannie Mae
Fannie Mae acts as a massive engine behind the scenes of the American housing market. While they are not a direct lender you walk into on a street corner, their technology and standards drive how many loans are actually made. They provide the framework that many professional lenders use to approve you.
When you hear a lender say they “follow Fannie Mae guidelines,” it means they are using a standardized, highly regulated process. This approach minimizes risk for both the lender and the borrower, making the whole system more predictable.
Their Desktop Underwriter system is a cornerstone of modern mortgage processing. By using advanced data and insights, they help lenders make faster, more accurate underwriting recommendations. This is the gold standard for those looking for highly regulated and standardized single-family financing options.
It reduces the “human error” element of mortgage approval. The result is a more clinical and predictable outcome for the borrower, which can take some of the anxiety out of the process.
Pros:
- Utilizes advanced Desktop Underwriter technology.
- Provides massive scale and stability to the market.
- Offers streamlined pricing through modern credit models.
Cons:
- Not a direct lender; you must work through a partner.
Preparing Your Financial Portfolio for Approval
Securing a loan for a manufactured home requires more than just a decent credit score; it requires a meticulous level of documentation. Because manufactured homes are often categorized differently than stick-built homes, lenders will be particularly eagle-eyed regarding your ability to repay and the collateral value of the home.
Start by gathering your “Big Three” documents: proof of income, tax returns, and asset statements. For manufactured home buyers, lenders often want to see at least two years of consistent employment history. This consistency proves you can handle the monthly payments over the long haul.
If you are self-employed, prepare for a much deeper dive into your cash flow. You may need to provide several months of bank statements to prove that your income is stable and not just a seasonal spike. Additionally, ensure your debt-to-income (DTI) ratio is as low as possible. Most lenders want to see that your total monthly debt obligations do not exceed 43% of your gross monthly income.
Navigating Your Path to Homeownership
The most common mistake people make is applying for the wrong type of loan for their specific property. A manufactured home is often treated differently than a site-built house. If you apply for a traditional mortgage for a mobile home, you might run into a wall of confusion and delays.
Always ask your potential lender, “Will this be a real property mortgage or a chattel loan?” before you submit a formal application. Knowing this early saves you weeks of frustration and wasted paperwork.
Another pitfall is ignoring the fine print regarding credit scores. Some lenders, like Sound Community Bank, have a specific floor for credit scores. If you fall even a few points below that mark, you might be wasting your time with that particular institution.
It is worth noting that while a score of 640 might get you through the door at one bank, a score of 680 or higher might unlock much more favorable interest rates at another. Always verify your score and the specific models lenders use before you start the paperwork.
Finally, do not wait until the last minute to check your credit. A sudden dip in your score can turn a “yes” into a “no” overnight. This can happen due to a high credit card balance, a small unpaid medical bill, or even a recent inquiry for a new line of credit.
Take the time to clean up your profile, resolve any discrepancies in your credit report, and understand exactly what you bring to the table before you start knocking on doors. A clean, organized profile is your greatest leverage in a negotiation.