

Top 5 Lenders for Bad Credit Loans in North Carolina: 2026 Rankings
Last updated: 2026-10-16
Trying to balance your books in North Carolina can feel like trekking through a dense swamp when your credit score isn’t exactly stellar. Many residents find themselves facing unexpected car repairs, like a sudden transmission failure in Raleigh, or urgent medical bills from a trip to an urgent care center in Charlotte. These unexpected costs require immediate cash to keep life moving forward without a hitch.
These financial shocks can derail a monthly budget in a single afternoon. Suddenly, families find themselves scrambling to cover essential costs like rent or electricity. It is a stressful position to be in when the money you set aside for groceries is suddenly needed for a utility bill.
Finding the right lender involves more than just glancing at the interest rate. You have to weigh speed and accessibility against the total cost of borrowing. A loan with a lower interest rate might seem attractive on paper, but if it takes ten business days to fund, it won’t help you if the power company is threatening to shut off your electricity tomorrow.
On the flip side, a “quick cash” option might provide the speed you need, but it could carry an APR that makes the total repayment much higher than you expected. This list clarifies which options might suit your specific situation during uncertain times. It helps you weigh the trade-offs between immediate liquidity and long-term affordability.
- FastLendGo
- Addition Financial
- PaydayPact
- Credit Human
- LoanStart
Evaluating Financial Assistance Across the Tar Heel State
The selection process for this ranking focused on how easily a borrower can secure funds when their credit history is less than perfect. We looked at the ease of the application process and the speed of funding. We also considered the flexibility offered to those with subprime scores.
We specifically scrutinized the user experience for ease of use. We noted whether applications could be completed on a smartphone while waiting in line at a clinic, or if they required a desktop computer and a pile of scanned documents. Convenience often dictates whether a lender is actually helpful in a crisis.
In North Carolina, high interest rates are a common side effect of easy approval. Because the risk to the lender is higher when a borrower has a low credit score, the price of that risk is reflected in the APR. Therefore, the ranking prioritizes lenders that provide clear pathways for those who might have been turned away by traditional big-box banks earlier in the week.
We looked for transparency in every option. We wanted to know: does the lender show the total repayment amount upfront, or do you only find out after you have signed the digital agreement? Knowing the final number before you commit is essential for anyone trying to manage a tight budget.
| Lender Name | Loan Amounts | Credit Requirements | Funding Speed | Terms |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000 | Bad Credit / Fair Credit | Same day or next business day | see site |
| Addition Financial | see site | see site | see site | see site |
| PaydayPact | see site | Guaranteed approval online | see site | see site |
| Credit Human | As little as $500 | No credit review | see site | Up to 72 months |
| LoanStart | Up to $40,000 | see site | see site | see site |
Ranking the Best Options for North Carolina Borrowers
1. FastLendGo
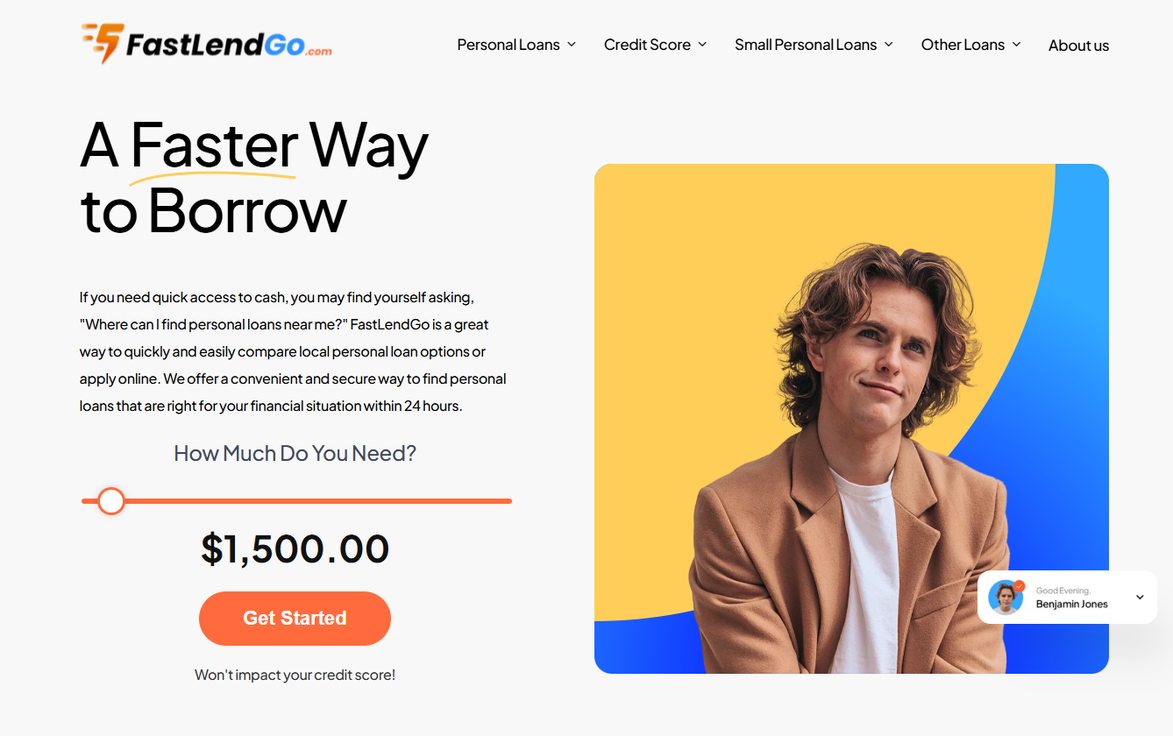
FastLendGo works well for those needing quick cash to cover immediate emergencies. Whether it is a sudden dental bill or a necessary auto repair, this service focuses on getting money into your hands without the usual mountain of paperwork. The streamlined digital interface is built for the modern consumer who needs to solve a problem in minutes rather than days. (fastlendgo.com)
This option is particularly suited for individuals who need specific amounts. You might need a $500 loan for a grocery bill gap or a $2,000 personal loan to fix a leaking roof. It caters to a wide spectrum of credit profiles, from those with bad credit due to a recent medical emergency to those with fair credit looking to build a better financial standing through consistent on-time repayments.
Pros:
- Offers various loan sizes from $500 to $5,000.
- Fast funding, potentially arriving the same day.
- No minimum credit score required to qualify.
Cons:
- Limited to specific smaller loan amounts.
2. Addition Financial
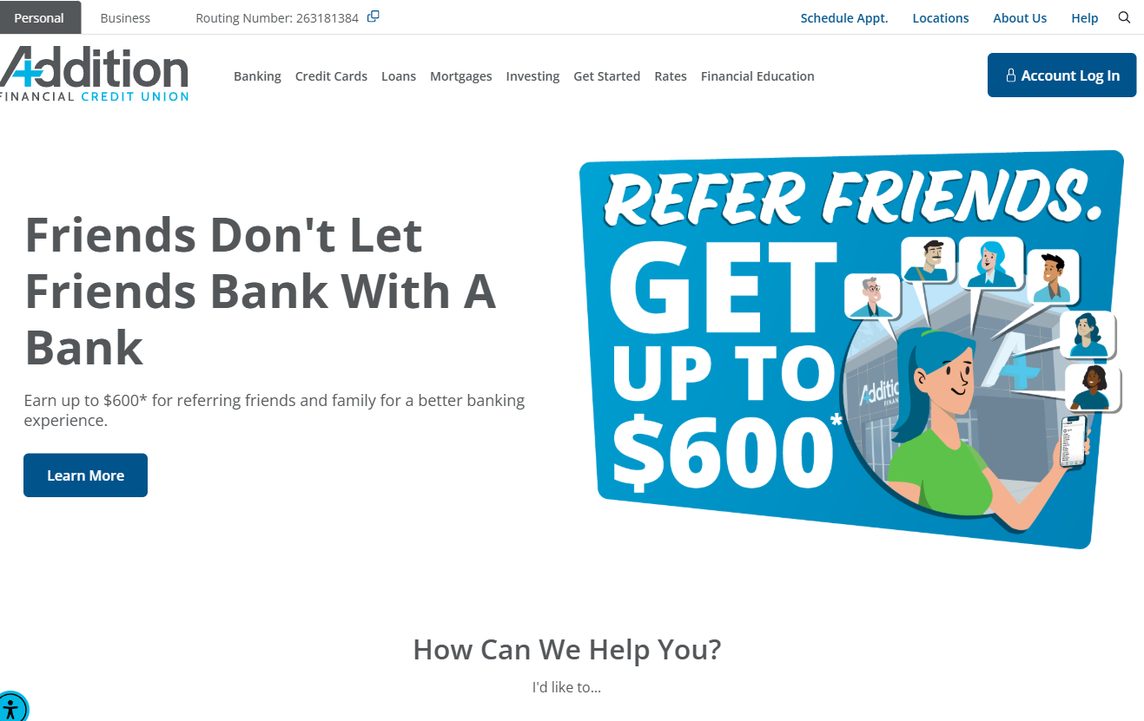
Addition Financial focuses on comprehensive banking needs beyond just quick cash injections. They offer a suite of products including checking accounts, credit cards, and mortgages. This makes them a more traditional choice for those looking to build a long-term relationship with a financial institution rather than just finding a one-off solution.
For members looking to grow their assets, they provide savings options and competitive rates. It is a solid choice if you want a stable institution rather than just a quick fix for an immediate financial crisis. If your goal is to move away from the high-interest cycle and toward traditional banking, this is a logical step.
Pros:
- Diverse range of banking products.
- Potential for earning through referrals.
- Comprehensive financial services.
Cons:
- May require more extensive documentation than quick-cash lenders.
3. PaydayPact
PaydayPact acts as a highly accessible digital portal for those facing rejection elsewhere. Their online system is designed to be secure and user-friendly. You can apply from any device, whether you are on a phone while commuting on a bus in Durham or on a laptop at home. This accessibility is crucial for people who may not have a fixed desk or a printer for paperwork.
The primary draw here is the promise of guaranteed approval online. This is a lifeline for someone who needs certainty in a moment of financial chaos. When you are facing a late fee on a rent payment, knowing you will get a “yes” or “no” immediately can significantly reduce the psychological stress of the situation.
Pros:
- High accessibility via mobile devices.
- Secure online application process.
- Focused on guaranteed approval.
Cons:
- High interest rates are common with this type of model.
4. Credit Human
Credit Human offers a more structured approach to borrowing with fixed rates. They provide a safety net for those who need to borrow as little as $500, but want the stability of a set repayment schedule. Because the rates are fixed, you won’t have to worry about your monthly payment changing unexpectedly due to market fluctuations.
One of their standout features is the ability to borrow without a traditional credit review. This makes them a very strong contender for anyone in North Carolina who is tired of being judged solely by a three-digit number on a screen. They may look at your broader financial stability, making them an excellent option for those who have had a temporary setback but are otherwise reliable.
Pros:
- Flexible repayment options up to 72 months.
- No credit review required for some products.
- Fixed rates provide predictability.
Cons:
- Terms can be long, leading to more total interest paid.
5. LoanStart
LoanStart functions as a matching service that connects borrowers with a network of affiliate lenders. Instead of looking at one single bucket of money, you are looking at a wide net of potential partners that might fit your specific needs. This is helpful because “one size does not fit all” in the lending world; what works for a student might not work for a small business owner.
This is the heavy hitter for those who need larger sums, with the potential to access up to $40,000. It is a great option for those who have maxed out credit cards and need a larger, structured installment loan to consolidate debt. By rolling several high-interest credit card balances into one larger loan, you can simplify your monthly finances and potentially save hundreds of dollars in interest over time.
Pros:
- Potential for high loan amounts up to $40,000.
- Free service that does not affect your credit score.
- Connects you to a wide network of partners.
Cons:
- You are at the mercy of the affiliate lender’s specific terms.
Comparing Loan Types: Quick Cash vs. Installment Loans
Understanding the difference between loan types is vital for North Carolina residents trying to manage their debt. Most lenders fall into one of two categories: Short-term/High-interest or Long-term/Installment loans. Choosing the wrong one can lead to a cycle of borrowing that is difficult to break.
| Feature | Short-Term Loans | Installment Loans |
|---|---|---|
| Typical Duration | Days to a few months | 12 to 72 months |
| Interest Rates | Very High (Often 300%+) | Moderate to High (10% – 36%) |
| Best Use Case | Immediate emergencies (e.g., a $200 utility bill) | Debt consolidation or large repairs (e.g., a $3,000 car engine) |
| Repayment Structure | Lump sum or frequent small payments | Fixed monthly installments |
If you are facing a one-time expense that will be cleared by your next paycheck, a short-term loan might be the fastest path. However, if the amount you need is larger than your next two paychecks combined, an installment loan is a much safer way to avoid a “debt trap.”
Strategies for Managing Debt After Borrowing
Securing funds is only the first step; the second, and often more difficult, step is managing the repayment. Many North Carolina residents find themselves in a position where they have successfully resolved their immediate crisis but are now burdened by the new loan. To avoid this, consider these three proactive steps:
- Automate Your Payments: Set up automatic transfers from your checking account to the lender the day after you receive your paycheck. This ensures you never miss a payment, which is crucial for protecting your credit score.
- Prioritize High-Interest Debt: If you have multiple loans, use the “avalanche method.” This involves paying the minimum on all loans but putting every extra dollar toward the loan with the highest interest rate first. This mathematically minimizes the total amount of interest you pay over time.
- Negotiate with Creditors: If you are borrowing because you cannot pay a medical bill or a utility bill, call the provider *before* you take out a loan. Many companies have hardship programs or can offer a payment plan that is much cheaper than the interest rate on a quick-cash loan.
Avoiding Common Pitfalls When Borrowing
When you are in a pinch, it is easy to sign a contract without reading the fine print. Always look for the “total cost of credit,” which tells you exactly how much you will have paid back by the end of the loan term. For example, a $1,000 loan with a high interest rate might require you to pay back $1,500 over six months. That $500 difference is the “cost” of the convenience.
Avoid the trap of taking out a loan just to pay off another high-interest debt unless the new loan has a significantly lower rate. If you are using a high-interest payday loan to pay off a credit card, you are effectively moving the debt from one expensive bucket to an even more expensive one. If you find yourself constantly cycling through short-term loans, you might be stuck in a debt spiral that is hard to escape. This is often a sign that the underlying budget needs restructuring rather than more credit.
Lastly, verify the legitimacy of the lender before providing any sensitive information. While the digital age makes borrowing easy, it also makes it simple for bad actors to mimic real companies. Scammers often use aggressive language, like “You have been pre-approved! Act now or lose the offer!” to pressure you into giving up your Social Security number or bank login details. Always use official, secure websites to protect your identity and your wallet. Look for the “https://” in the URL and ensure the site has a padlock icon in the address bar before entering any personal data.