

Top 6 Land Loans for Bad Credit Options in 2026
Last updated: 2026-10-17
Finding the right dirt is often easier than finding the money to buy it. For many dreamers, the idea of owning a slice of the countryside or a quiet wooded lot feels just out of reach. Credit histories often act as a wall. Traditional banks frequently turn up their noses when a score dips below certain numbers, often demanding a 20% to 30% down payment that most first-time buyers simply do not have sitting in a savings account.
They view raw land as a high-risk asset. Unlike a residential home, land doesn’t offer a physical structure to serve as collateral if the loan goes sour. This makes securing financing a bit of a climb. You have to find lenders who see the value in the soil rather than just the digits on a credit report.
This list focuses on finding paths through those financial hurdles. Whether you want a small garden plot, a few acres for a weekend retreat, or a massive acreage for a homestead, you need to know your options. Understanding the difference between a “raw land loan” (land with nothing on it) and a “finished lot” (land with utility access and road frontage) is your first step toward matching with the right capital provider.
- Acorn Finance
- JetzLoan
- LightStream
- Country Bank
- Lendersa
- USDA
How These Land Loan Options Were Evaluated
The evaluation process focused on accessibility for different credit profiles. Not every lender is built for the same purpose. It is vital to know the distinction between personal loans, hard money, and government-backed programs. A lender that provides a quick cash injection might not be the right fit for a long-term mortgage. For example, a personal loan might offer speed, but you will likely face a higher interest rate than a traditional mortgage secured by the property itself.
Conversely, a traditional mortgage might take 45 days to close. In that time, your dream property might be sold to someone else. Speed of funding and the impact of credit inquiries were also key metrics. Some providers allow you to check rates without hurting your score. This is a lifesaver when you are trying to understand your borrowing power before committing to an offer.
We prioritized transparency. We looked at how quickly funds move, the complexity of the application, and what kind of collateral is actually required for the deal. We looked specifically at whether the lender requires a “hard pull” that stays on your report or a “soft pull” which is just an inquiry for informational purposes. It makes a world of difference when you are on a tight budget.
| Lender Name | Max Loan Amount | Funding Speed | Credit Requirement | Best For |
|---|---|---|---|---|
| Acorn Finance | See site | See site | Good & Bad Credit | Contractor/Home Improvement |
| JetzLoan | $50,000 | 24 Hours | No Hard Pull Check | Fast Cash/Debt Consolidation |
| LightStream | $100,000 | See site | Good to Excellent | High Credit Borrowers |
| Country Bank | See site | 60 Day Rate Lock | Subject to Approval | Raw Land/Buildable Lots |
| Lendersa | See site | Fast Closing | Varies (Hard Money) | Fix and Flip/Investors |
| USDA | See site | See site | Varies | Rural Development/Homes |
Ranking of Land Loan Providers
1. Acorn Finance
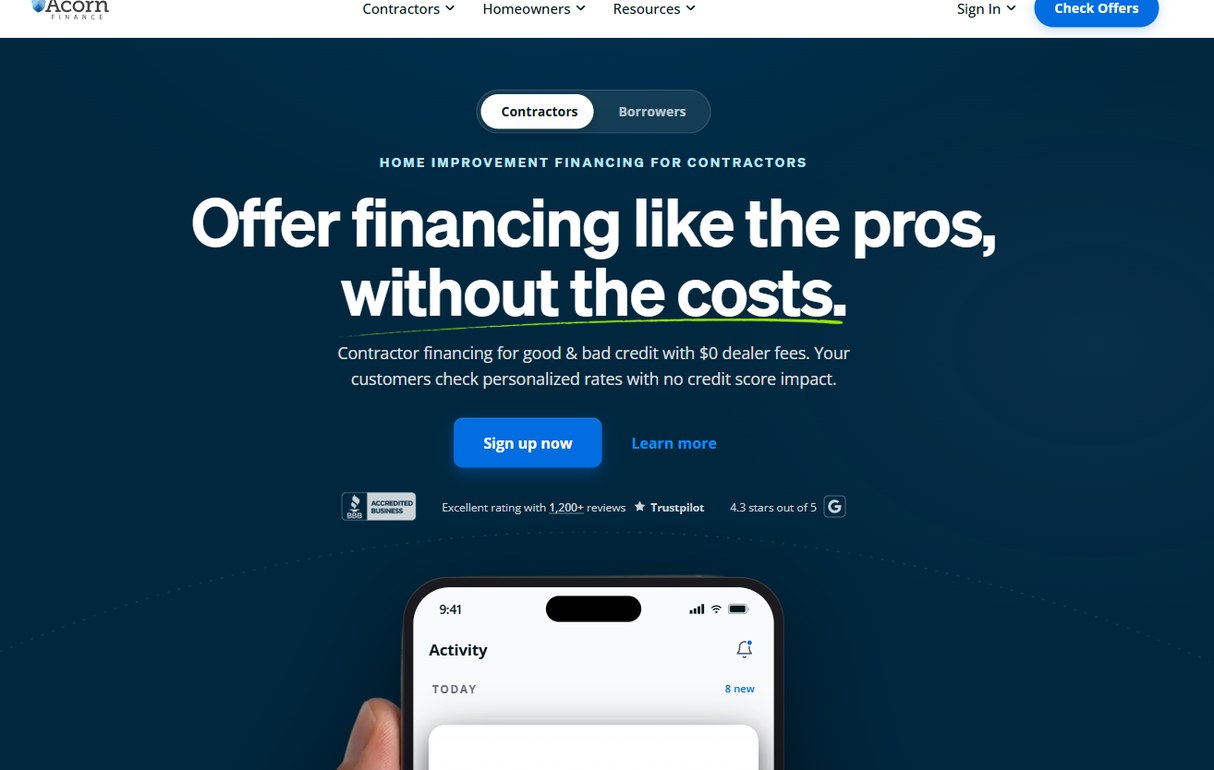
Acorn Finance acts as a bridge between borrowers and various financing options. They specialize in providing $0 dealer fees. This is a breath of fresh air in an industry known for hidden costs and service charges that can add thousands to your total loan amount. It is a solid choice if you need to combine land acquisition with immediate improvements, such as clearing trees or installing a driveway.
This provider is particularly useful for those who need to get a project moving quickly. Because they cater to both good and bad credit, the barrier to entry is significantly lower than a standard big-box bank. Instead of being judged solely on a FICO score, the variety of lenders they connect you with means there is a higher probability of finding a specialist who understands your specific situation.
It is a practical tool for the modern borrower who needs flexibility. You won’t find yourself stuck in a loop of denials if you have a complicated financial history. They focus on matching you with someone who can actually say “yes” to your project.
Pros:- $0 dealer fees for contractors and borrowers
- Personalized rates with no credit score impact during checking
- High customer satisfaction with 4.3 stars on Trustpilot
- May not offer the lowest rates compared to prime lenders
2. JetzLoan
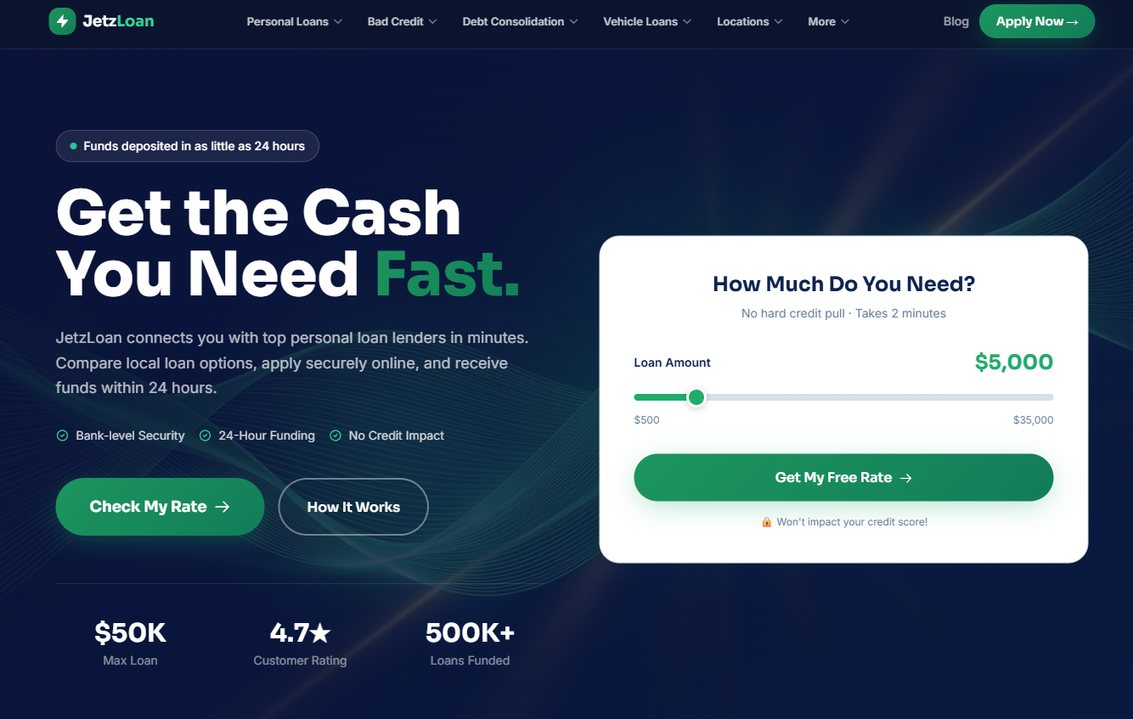
When time is of the essence, JetzLoan moves with impressive speed. They can deposit funds in as little as 24 hours. This makes them a go-to for urgent land deals or consolidation. This speed is essential in competitive markets where a seller might be looking for a “cash offer” to bypass the lengthy appraisal and inspection processes required by traditional banks.
The application process is remarkably streamlined. It takes only about two minutes to complete. This makes it an ideal option for someone who has found a parcel of land at an auction and needs to secure funds immediately to show proof of capability. The ability to check rates without a hard credit pull is a major advantage for those with sensitive credit. This allows a borrower to shop around without fear of further damaging their score.
It is a high-speed option for a fast-paced market. If you find that perfect lot on a Friday afternoon, you don’t want to be waiting until next month to prove you can pay for it. JetzLoan fills that gap for those who need to act fast.
Pros:- Funding in as little as 24 hours
- No hard credit pull to check rates
- High loan limits up to $50,000
- Limited to personal loan structures rather than traditional land mortgages
3. LightStream
LightStream is a different beast entirely. They cater to those who have already climbed the credit ladder. They offer low fixed rates that are hard to beat if you have good to excellent credit. It is a premium service for those who want stability and predictability. You can lock in a rate and know exactly what your monthly payment will be for the duration of the loan.
The loan amounts can reach up to $100,000. This provides significant breathing room for substantial land purchases or for purchasing a large plot to subdivide. However, if your credit is currently in the “bad” category, this particular door will likely remain closed. They use automated underwriting processes that prioritize high FICO scores and stable income history.
It is a destination for the credit-worthy who want to avoid the higher interest rates of subprime lenders. If your finances are in order, this is often the most efficient way to move forward. They make the process incredibly smooth for those who meet their criteria.
Pros:- Low fixed interest rates
- Loan amounts up to $100,000
- Highly reputable through Truist
- Requires good to excellent credit; not for bad credit
4. Country Bank
Country Bank offers a more traditional, community-focused approach to lending. They are an FDIC-insured institution that understands the nuance of land in ways a large national bank cannot. While a national bank might reject a loan for a lot that has no paved road access, a community-focused bank understands the local zoning laws and the intrinsic value of that specific piece of geography.
One standout feature is their 60-day rate lock, which provides a sense of security in a volatile market. This allows a buyer to plan their next steps, such as hiring an architect or a surveyor, without worrying that interest rates will spike before they can close the deal. They provide tailored solutions for both raw land and buildable lots. They recognize that the risk profile of each is vastly different.
This is a great choice for someone looking for a long-term relationship with their lender. They know the area and they know the land. That local knowledge can be the difference between a deal falling through and a deal closing smoothly.
Pros:- 60-day rate lock availability
- FDIC-insured security
- Offers financing for both raw and buildable land
- Standard bank approval processes can be rigorous
5. Lendersa
Lendersa is built for the investor who needs to move at the speed of light. Using AI to match borrowers with hundreds of hard money lenders and private investors, they optimize for closing speed. This is a high-octane option for real estate professionals who specialize in land flipping or quick acquisitions for development projects. While a traditional bank might take weeks to verify surveys, Lendersa’s network is built for rapid movement.
If you are looking to jump into an auction or a fast-moving “fix and flip” scenario, this is where you look. They focus on getting the deal closed in days rather than months. This is crucial when competition is fierce and a seller demands a quick close. They cover both residential and commercial property types, providing a wide net for diverse investment strategies.
It is not for everyone, as the terms are often quite different from a standard mortgage. However, for the professional investor, the speed can be worth the premium. It is all about how fast you can turn the property around for your next move.
Pros:- Uses AI to match lenders and optimize rates
- Designed for fast closing and auctions
- Covers residential and commercial property types
- Hard money terms can be much more expensive than traditional loans
6. USDA
The USDA is a government-backed option that focuses on the backbone of the country: rural development. They provide loans and grants aimed at helping people buy, build, or repair homes in specific rural areas. This is a mission-driven approach to lending designed to prevent rural depopulation by making it easier for young families and homesteaders to establish roots.
This is an excellent path for those looking to live in a rural setting and build a life from the ground up. The programs are designed to strengthen rural economies and expand opportunities for families who might otherwise be overlooked due to low down payments or specific income requirements. If you qualify, this can be one of the most affordable ways to acquire property in the country.
It requires a bit more paperwork and a specific location, but the payoff is significant. It is a program built for people, not just for profit. If you fit the criteria, it is a very powerful tool for homeownership.
Pros:- Government-backed stability and support
- Focuses on rural economic development
- Offers various programs including grants and loans
- Strict geographic requirements for eligibility
Understanding Land vs. Home Loans
Before applying, it is vital to understand the fundamental differences in how lenders view land versus a residential house. When you buy a house, the building itself acts as security. If you stop paying, the bank can sell the house and recoup their money. When you buy land, the security is just the dirt. If the market for that specific area dips, the land may not be worth what you paid for it, making it much riskier for the lender.
Because of this risk, land loans often require more from the borrower. You might face higher down payments, often 20% to 50% for raw land. You may also see higher interest rates than traditional residential mortgages. Lenders often demand more extensive documentation regarding access, easements, and utilities. In some cases, especially with hard money, you might even see short-term repayment options.
Essential Steps for Securing Your Land Deal
To ensure you aren’t left with a beautiful piece of property that is impossible to live on, follow these specific steps during your due diligence phase:
- Verify Access: Never assume a dirt path is a legal right-of-way. Ensure the property has “legal access” to a public road. Without this, the land is virtually unmarketable and unfinanceable.
- Check Utilities: Ask for a “perc test” if you plan to install a septic system. If the soil doesn’t drain properly, you might be unable to build a home. Additionally, check the cost to bring electricity to the site; running power lines can cost tens of thousands of dollars.
- Review Zoning: Just because it is “rural” doesn’t mean you can build whatever you want. Check local ordinances for setbacks, minimum acreage requirements, and restrictions on livestock or structures.
- Survey the Boundaries: Don’t rely on old fences or “handshake” agreements with neighbors. A professional survey is the only way to ensure you are actually buying the acreage you think you are.
Choosing a lender is not a one-size-fits-all endeavor. If you are an investor needing to move on a property immediately, a hard money lender like Lendersa might be your best bet, even if the cost is higher. If you are a long-term resident looking for stability, a traditional bank or a USDA program might be more appropriate.
One common mistake is failing to account for the “hidden” costs of land. Unlike a house, land often requires immediate investment in road access, water, and electricity. Always ensure your loan amount leaves room for these essential infrastructure upgrades. If you use your entire budget to buy the dirt, you may find yourself owning a beautiful view that you cannot actually reach or inhabit.
Always remember to check the impact of your inquiry. Utilizing lenders like JetzLoan or Acorn Finance that offer no-impact rate checks can save your credit score from unnecessary dents. Knowledge is power, and in the world of land lending, information is your best tool for success. Take your time, do your homework, and ensure your financing matches your long-term vision for the land.