

Last updated: 2026-10-24
If you’re in Missouri looking for cash to fix a car or start a home project, your options depend on whether you need money immediately or want a structured bank loan. Some lenders prioritize speed for people with various credit scores, while traditional banks are better if you have an established history and want more stability. The decision-making process often boils down to a trade-off between convenience and cost. For instance, if your transmission fails on a Tuesday and you need the car running by Thursday, you’ll likely sacrifice interest rate savings for the sake of speed. Conversely, if you are planning a kitchen remodel for next season, you have the luxury of shopping around for the lowest possible APR.
1. Empire Finance
2. BMO
3. MissouriLend
4. Western Shamrock
You’ll need to weigh how fast you can get the cash against how much that debt will actually cost you. A fast loan is great in an emergency, but the interest rates are usually much higher than what you’d get at a major bank. Picking a provider is really about matching the loan terms to what you actually need. You must consider the “Effective APR”—the total cost of borrowing including any origination fees or processing costs, rather than just looking at the monthly payment amount. A $500 loan with a $50 fee is much more expensive than it looks if you only intended to borrow it for two months.
How We Compared the Top Missouri Lenders
We looked at these lenders based on whether they actually work for Missouri residents and the types of products they offer. We checked how much you can borrow, how fast the money hits your account, and how easy the application is. We also looked at how they operate, noting if they’re mostly digital or have physical branches you can actually visit. This is crucial in Missouri, where accessibility can vary significantly between a tech-heavy startup in St. Louis and a community bank with a single branch in a rural county.
We focused on four different types of lenders for this list: national banks, online marketplaces, and local installment lenders. This mix covers a lot of ground, so whether you have great credit or just need a small, short-term amount, there’s something here that fits. We evaluated them across several key metrics: the speed of the underwriting process, the flexibility of repayment terms, and the transparency regarding credit inquiries. We wanted to ensure that a Missouri consumer could find a solution whether they were facing a minor repair or a major life event.
| Lender Name | Loan Amount Range | Speed of Funding | Best For |
|---|---|---|---|
| Empire Finance | $200 to $1,525 | see site | Short-term installment loans |
| BMO | $1,000 to $35,000 | see site | Unsecured personal loans |
| MissouriLend | $500 to $35,000 | Within 24 hours | Fast online comparisons |
| Western Shamrock | $150 to $3,750 | see site | Installment loans |
1. Empire Finance
Empire Finance provides short-term consumer finance. They offer installment loans specifically to people with good credit who need a set amount of cash quickly without a long-term commitment. This type of lender is ideal for “gap financing”—that extra $500 you didn’t realize you needed to cover a sudden medical bill or a car repair that exceeds your emergency fund.
You can borrow anywhere from $200 to $1,525. Because the amounts are relatively small, they’re better for immediate needs rather than large debt consolidation or big purchases. Because they focus on a specific, smaller niche, their approval process is often streamlined to avoid the weeks of paperwork typically required by large-scale mortgage or personal loan providers. They do have staff available to help walk you through the application, which can be a major relief if you are confused by the digital paperwork.
Pros:
- Low minimum loan amounts for small needs
- Quick application process
Cons:
- Relatively low maximum borrowing limit
- Focuses on a specific credit profile
2. BMO
BMO is a massive financial institution. For personal loans, they offer unsecured options, meaning you don’t have to put up collateral like your home or your car title. These work well if you want to manage a larger expense through a set repayment plan. Because they are a major bank, they offer a sense of permanence and established regulatory oversight that some smaller, digital-only lenders may lack.
The bank offers loans from $1,000 to $35,000. According to mybanktracker.com, their terms can last between 12 and 72 months. This lets you spread payments out over a few years to keep monthly costs lower. For example, if you borrow $10,000, a 60-month term might make the payment very manageable, though you will ultimately pay significantly more in interest over that five-year span than you would with a 24-month term.
Pros:
- High maximum loan amounts
- Longer repayment terms available
Cons:
- Likely requires higher credit scores
- Traditional banking requirements may be stricter
3. MissouriLend
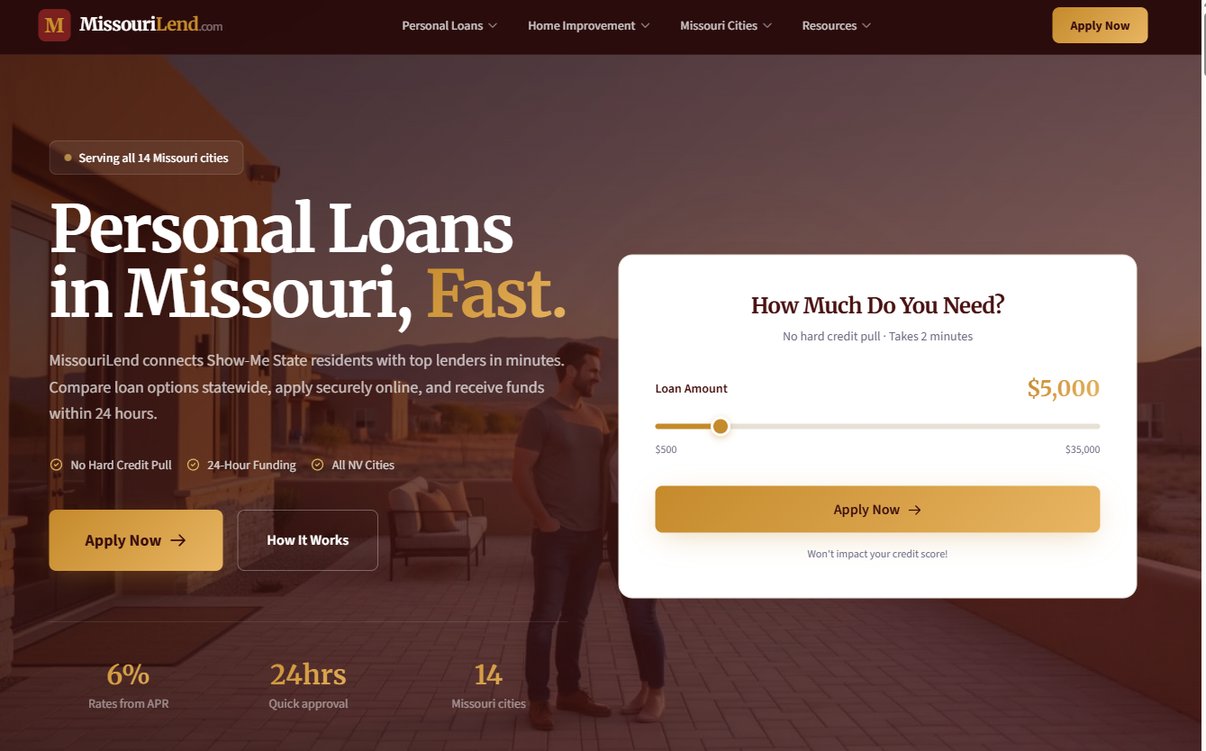
MissouriLend connects Missouri residents with top lenders. It’s a digital-first setup where you can compare options without a hard credit pull, so checking your rate won’t hurt your credit score. This “soft pull” feature is a massive advantage for consumers who want to shop around for the best deal without the fear of seeing their FICO score drop by several points during the research phase.
They focus on speed. They offer Missouri personal loans online that can result in funding within 24 hours. They operate in 14 Missouri cities and have rates starting at 6% APR. The whole process starts with a quick two-minute check to see what you qualify for. This makes them a premier choice for the “online researcher” who wants to see a variety of competitive offers without visiting a dozen different websites.
Pros:
- No hard credit pull for initial rates
- Very fast 24-hour funding goal
Cons:
- Rates depend heavily on individual eligibility
- Acts as a marketplace rather than a direct lender
4. Western Shamrock
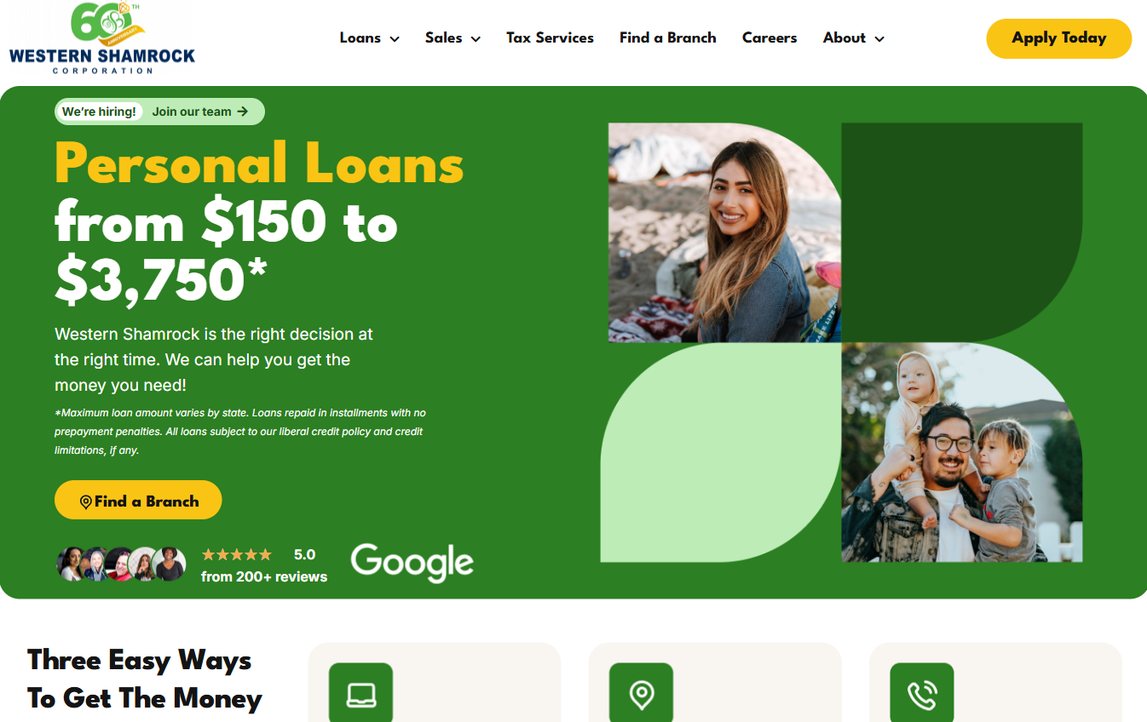
Western Shamrock is a direct lender that does installment loans. You can apply online, in person at a branch, or over the phone, which gives you a bit more control over how you handle the application. This multi-channel approach is helpful for people who aren’t comfortable completing complex financial documents entirely online and prefer the accountability of speaking to a human being.
Their loans run from $150 up to $3,750. One thing to note is that all loans are repaid in installments and they don’t charge prepayment penalties. If you have extra cash later, perhaps from a tax refund or a work bonus, you can pay the debt off early without a penalty. This is a significant advantage, as many high-interest lenders try to bake their profit into the interest you would have paid over the full life of the loan; Western Shamrock allows you to save money by being proactive.
Pros:
- Multiple ways to apply
- No prepayment penalties
Cons:
- Lower maximum loan amount compared to banks
- Credit limitations apply to all loans
Understanding Loan Types: Secured vs. Unsecured
Before applying, you must understand the fundamental difference between secured and unsecured loans, as this affects your risk and your interest rate. An unsecured loan, like those offered by BMO, is based entirely on your promise to pay. Because the lender has no collateral to seize if you default, they typically charge higher interest rates and require better credit scores. This is the “cleanest” way to borrow because your car or home isn’t on the line.
A secured loan, on the other hand, uses an asset, like a vehicle title, as collateral. If you cannot repay the loan, the lender has the legal right to take that asset. While this makes it much easier to get approved (even with lower credit), it carries much higher stakes for your personal property. In Missouri, many small installment lenders focus on unsecured options to simplify the process, but always be certain about what you are signing before you provide asset information.
Steps to Prepare for Your Missouri Loan Application
To increase your chances of approval and secure the best possible interest rate, follow these preparatory steps:
- Gather Documentation: Have your last two pay stubs, a recent utility bill (to prove Missouri residency), and your social security number ready. Digital lenders often require a photo of your ID.
- Check Your Credit Score: Even if you use a marketplace like MissouriLend that offers soft pulls, knowing your score beforehand helps you set realistic expectations for the rates you’ll be offered.
- Calculate Your Debt-to-Income Ratio (DTI): Lenders look at how much of your monthly income already goes toward debt. If your rent and existing car payments take up 50% of your paycheck, you may find it difficult to qualify for new funds.
- Verify Your Monthly Budget: Before signing, look at your monthly cash flow. If you are taking a $3,750 loan, can you comfortably afford the monthly installment alongside your groceries and gas?
How to Choose a Loan in Missouri
The biggest mistake people make is ignoring the total cost. A low monthly payment looks good on paper, but if the term is too long, you’ll end up paying way more in interest by the end. For example, a $5,000 loan with a $150 monthly payment sounds affordable, but if that term lasts 48 months, you will have paid $7,200 total, meaning $2,200 in interest alone. Always check the total amount you’ll have paid back once the loan is finished.
Check the lender’s requirements before you even start. If you need money by tomorrow, a traditional bank is probably too slow, and you’d be better off with an online lender or a local installment shop. On the flip side, if you need $20,000 for a renovation, a small installment lender won’t be able to help. Match the amount and the timeline to what the lender is actually built to do. Take the time to compare the “Total Cost of Credit” across at least two different providers to ensure you aren’t overpaying for convenience.