


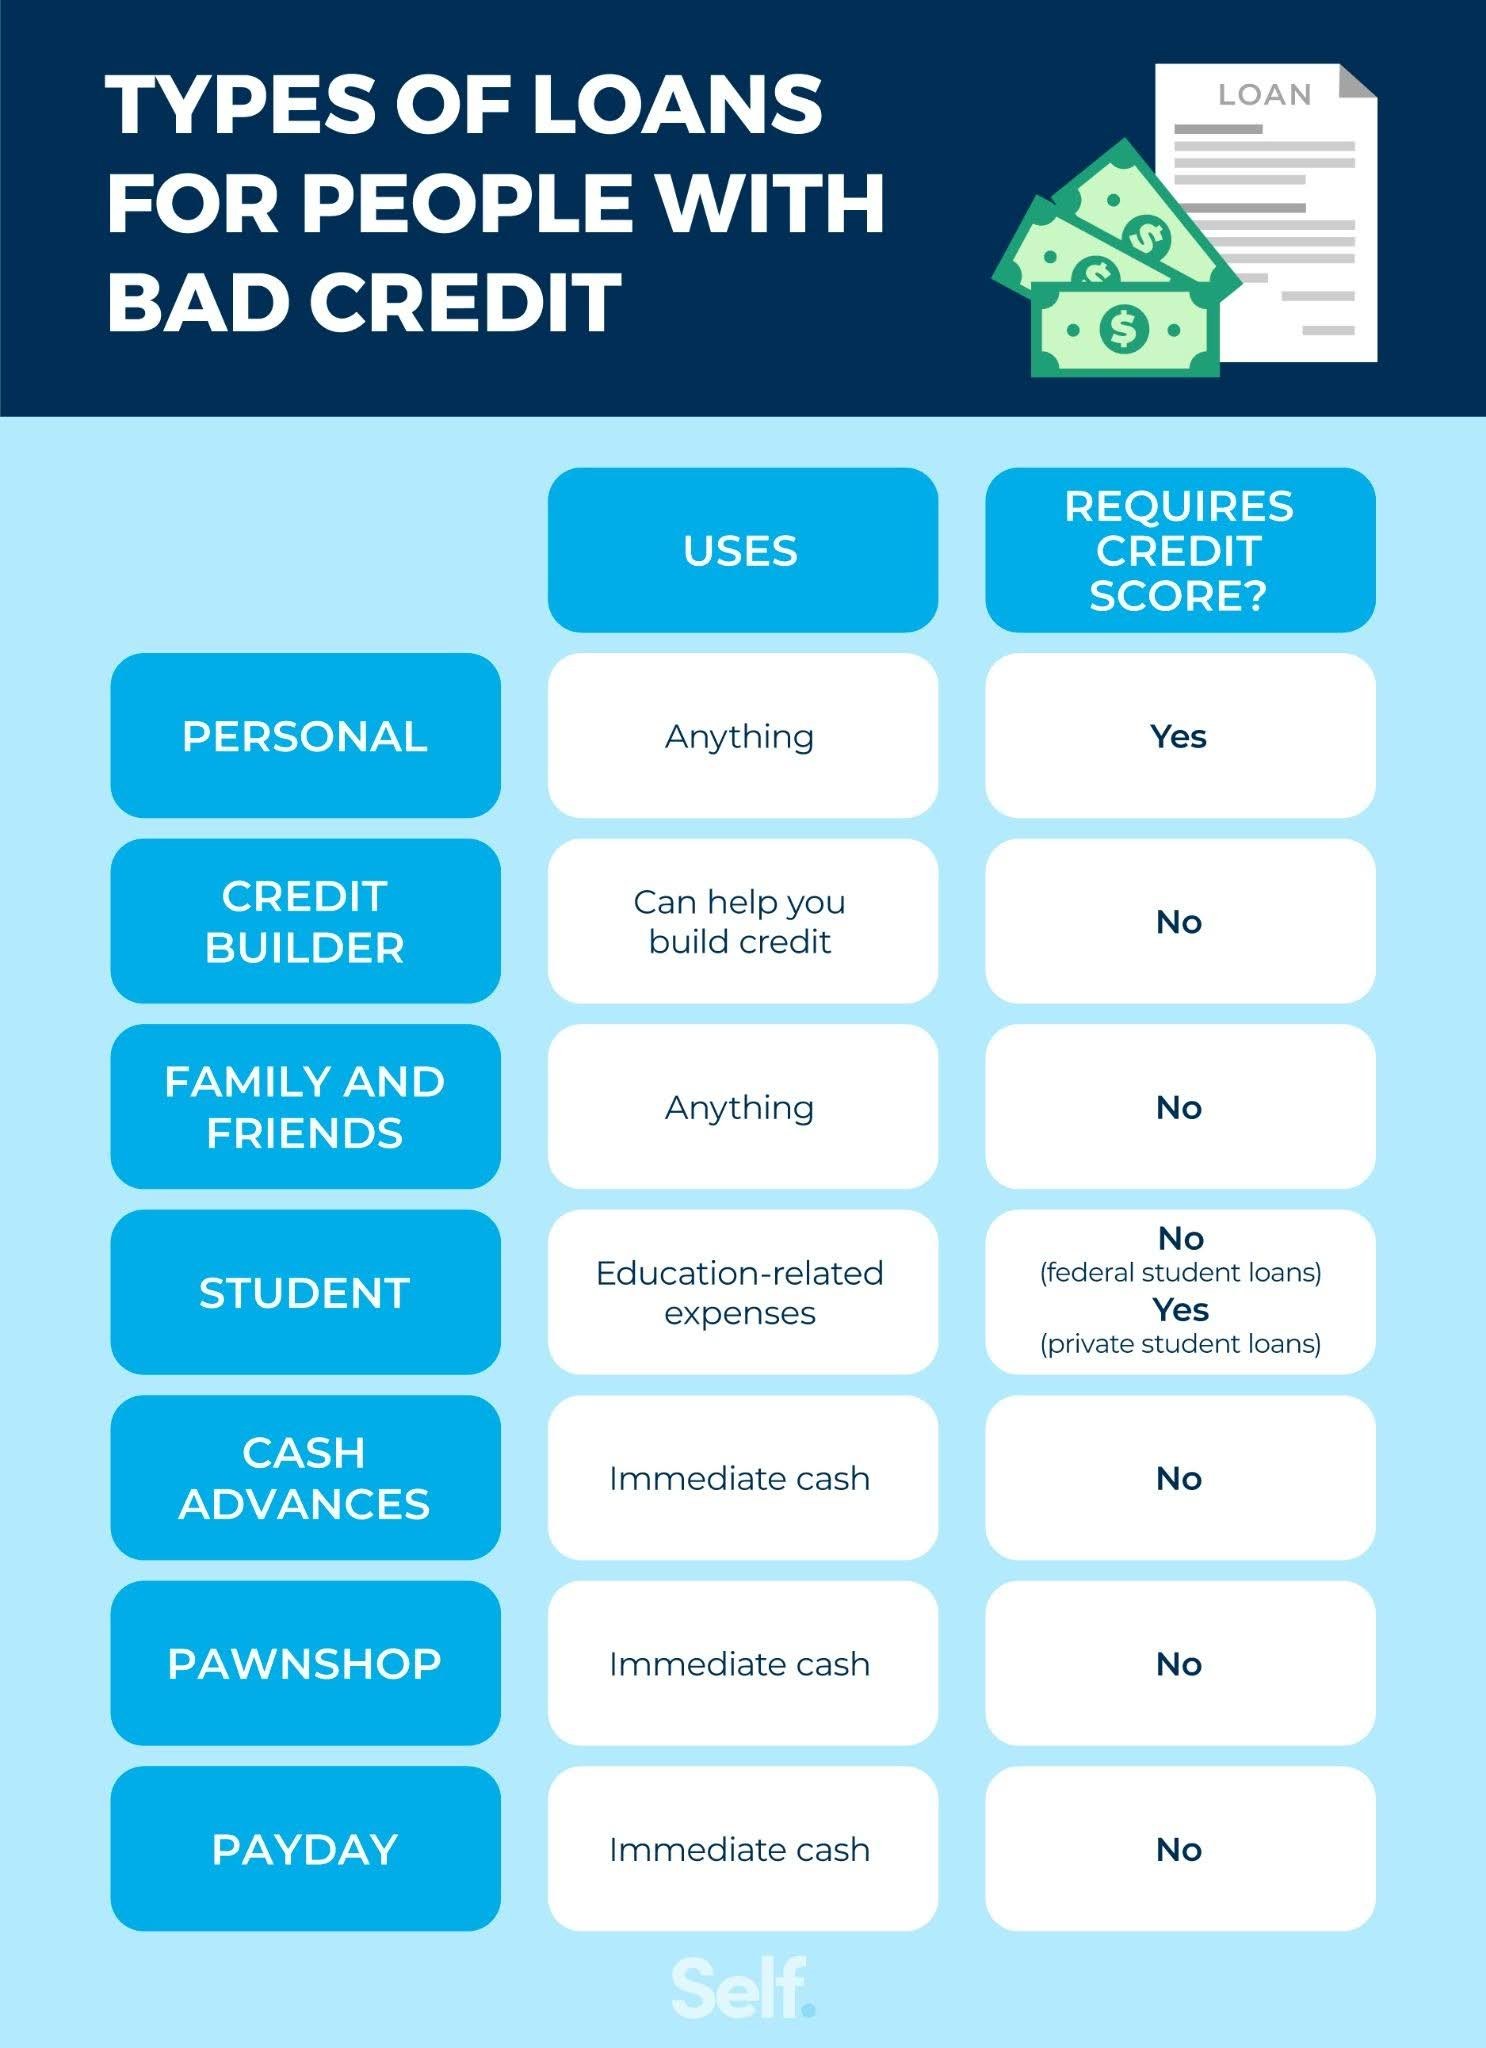
Most financial advice tells you to wait until your credit score is pristine before even thinking about applying for a loan. That is often terrible advice if you’re facing a genuine emergency. If you’re sitting there with a 550 score and a mounting pile of bills, waiting eighteen months for a “healthy” score isn’t a strategy, it’s a recipe for a crisis. You can actually secure capital even when your credit history looks like a crime scene, provided you stop looking at traditional big-box banks and start looking at niche lenders.
Yes, you can get a personal loan with bad credit. It’s not a myth, and it’s not always a scam. While the interest rates will likely be higher than what someone with a 750 score gets, the money is accessible if you know where to look and how to present your case. You don’t need a perfect history; you just need a way to prove you can pay the money back starting today.
The reality is that lenders aren’t just looking at that single three-digit number. They want to see income stability, a clear debt-to-income ratio, and a sense that you aren’t going to disappear into the night. If you can show them that your current income covers your existing obligations, you have a fighting chance, even if your past mistakes are still haunting your credit report.
Finding the Right Lenders Without Destroying Your Score
The biggest mistake people make is “shotgunning” applications. They see a dozen different ads, click every single one, and hit “submit” on five different applications in a single afternoon. Every one of those hard inquiries can ding your score. Instead, use tools that let you see your options without the risk. For example, you can use Sunward Instant Loan Pre-Qualification to get a personalized loan estimate for an auto loan, personal loan, or even a credit card in just a few minutes. The best part is that it won’t touch your credit score during the checking process.
But you have to be careful about where you end up. There is a massive difference between a specialized lender and a payday loan shop. Payday lenders are the predatory wolves of the financial world. They’ll trap you in a cycle of high-interest debt that is nearly impossible to escape. You want a legitimate lender that operates online and offers structured repayment terms. Many direct lenders allow you to apply, get approved, and receive funds directly in your account without needing to walk into a physical branch.
When you’re comparing these options, look at the total cost of the loan, not just the monthly payment. A low monthly payment sounds great when you’re struggling, but if it’s spread over five years at a 35% interest rate, you’ll end up paying back three times what you borrowed. It’s a math problem that requires a cold, hard look at your monthly budget. If you find yourself needing a larger sum, such as a 25000 personal loan, the interest rate differences become even more massive, so you have to be incredibly disciplined about your comparison shopping.
It helps to have a checklist before you even open a browser tab. Don’t just wing it. You need to know your numbers. If you go into a lender’s website without knowing your exact monthly income or your total outstanding debt, you’re playing a losing game of guesswork. Being prepared makes you look more stable, and stability is the currency of the lending world.
- Check your score: Use a free tool so you know exactly what the lender is seeing.
- Verify income: Have your recent pay stubs or tax returns ready to upload.
- List your debts: Know the total amount you owe on car loans, student loans, and other cards.
- Compare APRs: The Annual Percentage Rate is the only number that truly tells you the cost of the money.
Why Unsecured Loans Are Your Best Bet for Recovery
When your credit is low, lenders will often ask for collateral. They might want your car title or your house as a guarantee that they get their money back. While this makes getting a loan easier, it also puts your most important assets on the line. If you miss a payment, they take your car. That is a high price to pay for a quick fix. This is why pursuing unsecured personal loans should be the primary goal if you have any way to qualify.
An unsecured loan doesn’t require you to pledge an asset. Instead, the lender relies on your promise to pay. This sounds risky to the lender, which is why they charge higher interest, but it is much safer for you. According to recent data, you can still get an unsecured loan even if you have a score of 629 or lower, provided you find the right specialty lender. These lenders have built their entire business model around people who have been rejected by the big banks.
Upstart is a notable example in this space, often cited as a top option for those with less-than-perfect credit. They offer loans ranging from $1,000 all the way up to $75,000 with various repayment terms, which provides a lot of flexibility. They look at things like your education and your employment history rather than just a FICO score. That’s a massive advantage for people who have had a temporary setback but are currently stable.
However, don’t assume that a high loan amount is always better. Sometimes, a smaller, shorter-term loan is the smarter move. If you use a $10,000 loan to pay off $10,000 in high-interest credit card debt, you’re essentially performing a “debt consolidation” maneuver. You are moving debt from a high-interest bucket to a lower-interest bucket, which is the fastest way to start rebuilding your score. It’s about working the system to your advantage rather than just throwing more debt at a hole.
Table: Comparing Loan Types for Bad Credit
| Loan Type | Collateral Required? | Risk to You | Typical Interest Rate |
|---|---|---|---|
| Secured Loan | Yes (Car, House, Savings) | High (Loss of asset) | Lower |
| Unsecured Loan | No | Moderate (Credit score) | Higher |
| Line of Credit | Sometimes | Variable | Variable |
The Steps to Navigating the Application Process
Getting a loan is a process, not a single event. You can’t just hope for the best; you have to actively manage the application. The first step is always the most boring but the most important: checking your own records. You need to know exactly what is on your credit report. If there is a mistake on there, like a debt you already paid off that is still showing as unpaid, fix it immediately. A single error can be the difference between an approval and a rejection.
Once you know your standing, you need to hunt for the right lenders. Don’t just look at the first result on a search engine. Use comparison tools that let you see multiple rates at once. You want to find a lender that specifically caters to your situation. Some lenders are looking for a 750 score, while others are perfectly happy to work with someone in the 580 range if that person has a steady job at a reliable company.
After you find a few candidates, apply. This is where you have to be meticulous. If the application asks for your annual income, don’t just give your base salary; include your bonuses and any other regular income you receive. If you leave money on the table in the application phase, you’re essentially telling the lender you can afford less than you actually can. They use your debt-to-income ratio to decide how much they are willing to risk on you.
And then there is the wait. Once you submit everything, the lender will do their deep dive. They might call your employer or ask for more documentation. This is normal. Don’t panic if they ask for a second copy of something you already sent. Being responsive and providing clean, clear documentation will speed up the process and make you look like a responsible borrower.
But don’t just stop once the money hits your bank account. That is where most people fail. The loan is a tool, not a windfall. If you take out a personal loan to cover your expenses but don’t change the habits that caused the expenses in the first place, you’re just digging a deeper hole. Use the loan to fix the problem, not to fund a lifestyle you can’t afford.
Avoiding the Trap of High-Interest Cycles
The biggest danger when you’re borrowing with bad credit is the “revolving debt” trap. This happens when you use a personal loan or a line of credit to pay off a credit card, but then you start using that credit card again for daily purchases. Suddenly, you have a personal loan payment *and* a new credit card balance. This is how people end up in a downward spiral that takes years to escape.
A line of credit can be a powerful tool if used correctly. As noted by some financial resources, you can apply for a line of credit online even with bad credit. A line of credit is flexible; you only pay interest on what you actually use. This makes it excellent for managing cash flow gaps or unexpected repairs. However, it’s also incredibly dangerous because the “available” credit feels like free money. It isn’t. It’s a debt waiting to happen.
If you’re using a loan to consolidate debt, make a vow to the person in the mirror: the old credit cards are being closed or at least tucked away. You cannot use the same money twice. If you find yourself looking at “instant” money options every time a car repair comes up, you don’t have a credit problem; you have a budget problem. A loan can solve a temporary liquidity crisis, but it cannot fix a permanent deficit in your income.
The most successful people I have seen come out of bad credit situations are the ones who treat the loan like a surgical strike. They use it for one specific purpose, paying off a high-interest debt or fixing a car so they can get to work, and then they immediately pivot back to aggressive saving. They don’t let the ease of modern online lending trick them into thinking that money is easy to come by. It is never easy, and it is never free.
The skeptics will say that if you have bad credit, no legitimate lender will ever give you a fair shake. They think the only option is a predatory payday lender or a high-interest shark. But they are wrong. The market has changed. There are many lenders who understand that a credit score is a snapshot of the past, while your current income and your future potential are much better indicators of whether you will pay them back. You just have to be willing to do the math and do the work to find them.
Questions people ask
Can I borrow money instantly if I have poor credit?
Yes, certain lenders specialize in bad credit loans and offer fast approval processes, though interest rates are typically higher.
Where can I get money immediately?
Immediate funds can often be obtained through online lenders, payday loans, or cash advances, depending on your eligibility and the lender's speed.
How to get 40,000 rupees urgently?
To get 40,000 rupees quickly, you can apply for instant personal loans through digital banking apps or specialized fintech lenders.
What is the biggest killer of credit scores?
The biggest killer of credit scores is a history of late payments or high credit utilization on existing debt.