

The 6 Best Lenders for Bad Credit Loans in Louisiana for 2026
Last updated: 2026-10-16
Trying to sort out your finances in Louisiana can feel like driving through a thick bayou fog without your headlights on. Many people here deal with credit scores that simply don’t show who they really are or their actual ability to pay back a loan. When a sudden car repair or an unexpected medical bill lands on your kitchen table, you need clear answers, not more confusion.
Whether you live in the busy streets of New Orleans or a quiet parish further inland, the pressure of money is a shared struggle for many hard-working Louisianans. Finding a lender that understands the reality of a low credit score is the first move toward getting back on your feet. This list looks at everything from local credit unions to digital lenders.
Each option offers a different route. You might need a quick cash infusion to get through the month or a long-term plan to consolidate nagging debts. Getting the right choice requires looking past the initial interest rate. You have to dig into the fine print of the terms, the conditions, and those repayment schedules.
- FastLendGo
- Coastline Credit Union
- LightStream
- United Finance
- Addition Fi
- GadCapital
How Louisiana Borrowers Are Evaluated
Picking a lender isn’t just a race to see who says yes the fastest. In the Pelican State, lenders look at several things, such as how steady your income is and your debt-to-income ratio. Credit scores are a big part of the puzzle, but they aren’t the only tool in the kit. Some lenders care more about your ability to pay them back through steady work.
For instance, a lender might ask for your last three months of bank statements to verify a consistent pattern of deposits. This can often carry more weight than a single dip in your FICO score caused by a one-time medical bill. Speed also matters when you are facing an emergency. If your car transmission dies on a Friday and you need to get to work by Monday, a two-week approval process might as well be a decade away.
We looked at these providers based on how accessible they are for people with less-than-perfect credit, how much they lend, and how fast they move from application to cash in hand. When you compare them, keep an eye on the “Total Cost of Borrowing.” This includes the interest rate along with any origination fees or administrative costs that might pop up during the closing process.
| Lender Name | Loan Amounts | Interest Rates | Funding Speed | Credit Requirements |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000+ | see site | see site | Bad/Fair Credit |
| Coastline Credit Union | see site | see site | see site | see site |
| LightStream | see site | 9.99% – 24.94% APR | Next day | Excellent Credit |
| United Finance | Up to $20,000 | see site | see site | see site |
| Addition Fi | see site | see site | see site | see site |
| GadCapital | $100 – $5,000+ | see site | Instant | No Credit Check |
Top-Rated Options for Louisiana Residents
1. FastLendGo
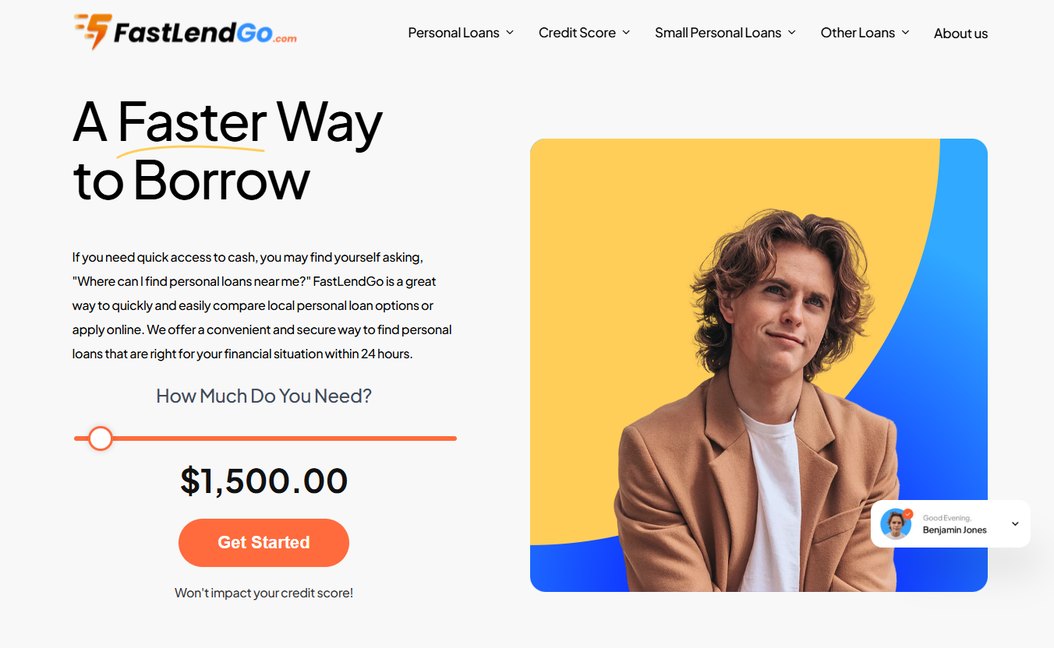
FastLendGo provides a way forward for people who might feel ignored by the big national banks. They specialize in various personal financing solutions, specifically for those who have a less-than-stellar credit history. Their digital-first approach aims to make the comparison process simple for local borrowers. You don’t have to drive from parish to parish to hunt for a specialist. You can evaluate your options right from your living room. (fastlendgo.com)
If you are facing a dental emergency or need to fix a leak in your roof, they offer several specialized loan types. Their platform handles everything from small $500 loans to larger $5,000 requests. It is built for people who need to move quickly without drowning in a mountain of paperwork. This makes them a useful tool for filling the gap between a sudden crisis and your next paycheck.
Pros:- Specializes in bad credit and fair credit loans.
- Offers specific loans for auto repairs and dental work.
- User-friendly online comparison tool.
- Lacks the personalized community feel of a local credit union.
2. Coastline Credit Union
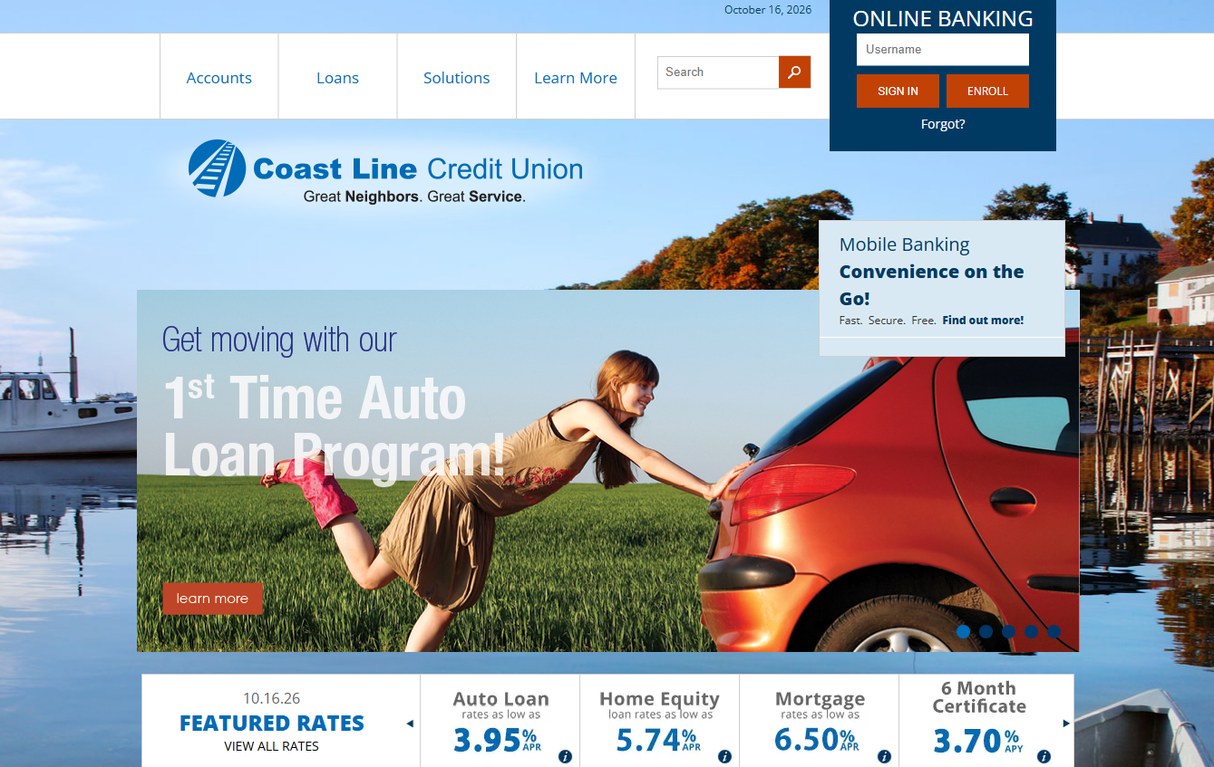
Credit unions are often the hidden gems of the financial world. Coastline Credit Union offers a more traditional, community-focused banking experience. For Louisianans who prefer a lender that feels like a neighbor rather than a faceless corporation, this is a strong contender. Because credit unions are member-owned cooperatives, their main goal is service rather than maximizing profit for shareholders. This often leads to more flexible terms for members.
They provide a variety of solutions, including standard loans and online banking features. While they might have stricter requirements than a payday lender, the relationship you build with a credit union can be incredibly helpful for your long-term financial health. If you maintain a steady relationship with them, you might find it easier to secure a mortgage or an auto loan later on, since they have a history of your reliability.
Pros:- Member-focused service model.
- Offers online and mobile banking convenience.
- Potential for better long-term rates through membership.
- May require membership eligibility.
3. LightStream
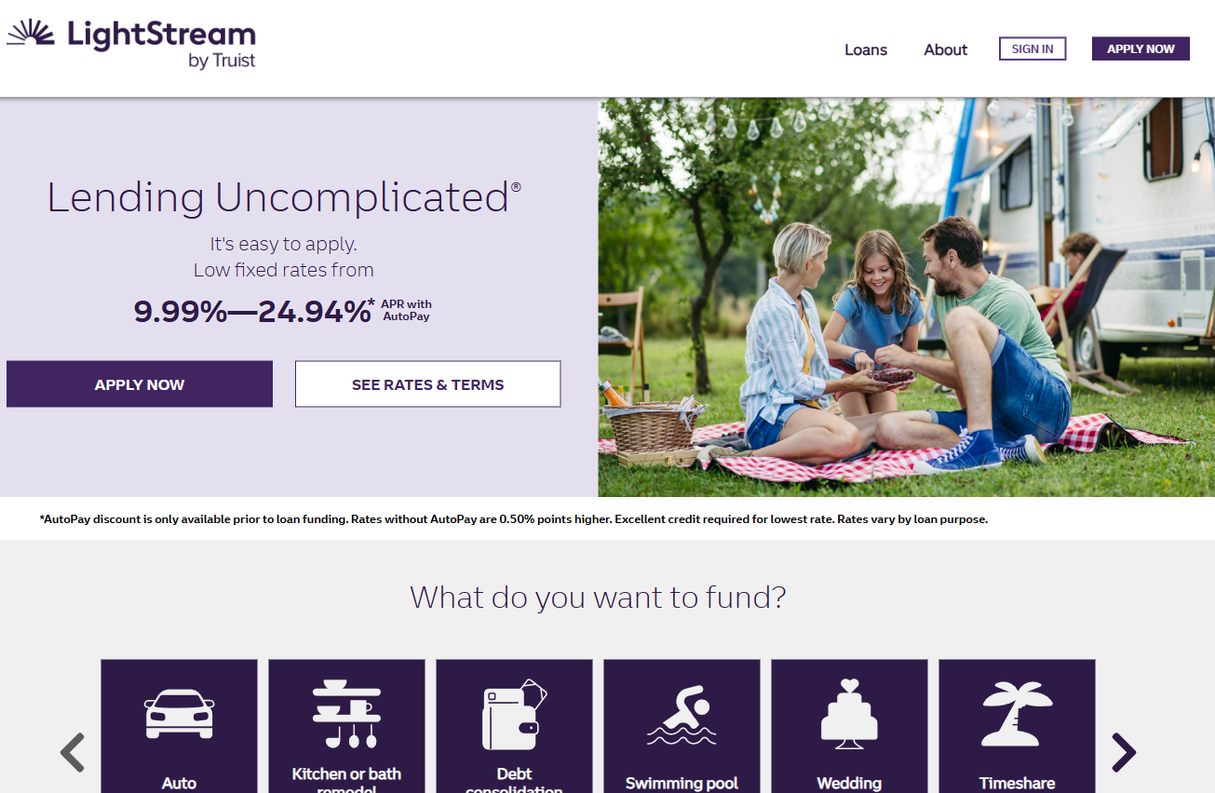
LightStream is a high-tier option for those who have worked hard to build a stellar credit profile. They aren’t the solution for someone currently in a deep credit hole. However, for those with excellent credit, they are hard to beat. They offer a streamlined application process that respects your time. This is an ideal choice for major life milestones where saving on interest can mean thousands of dollars over the life of the loan.
The platform is versatile, allowing you to fund everything from home remodels to wedding expenses. Their speed is impressive; many users report having funds in their accounts as quickly as the next day. This makes them a favorite for significant, planned life transitions. If you want to consolidate high-interest credit card debt into a single, lower-interest payment, LightStream’s structure is built for that exact purpose.
Pros:- Extremely fast funding, sometimes by the next day.
- Low fixed rates with AutoPay discounts.
- Highly versatile loan purposes.
- Requires excellent credit to access the best rates.
- Not suitable for those with poor credit.
4. United Finance
United Finance is a seasoned veteran in the lending space, having been around since 1922. They bring a level of stability that is hard to find in the modern era of fintech. They offer both personal and auto loans designed to fit into a realistic budget. Their longevity in the market shows they can handle changing economic climates, from the Great Depression to the digital revolution.
Their approach focuses on making personal loans simple and accessible. They provide a dedicated team of friendly lenders to help guide you through the process. This human element is vital if you find digital applications confusing or overwhelming. It is especially helpful for borrowers with complex financial situations, such as self-employment income, that an automated algorithm might automatically reject.
Pros:- Decades of experience and stability.
- Personal loans available up to $20,000.
- Offers auto loans and refinancing options.
- More traditional structure may be slower than digital-only lenders.
5. Addition Fi
Addition Financial operates with a focus on helping members grow their wealth and manage daily banking. They are more than just a lender; they act as a full-service financial partner. From checking accounts to investment options, they aim to be a one-stop shop. This allows members to see their entire financial life in one place, making it easier to track spending and savings habits.
They offer competitive rates and encourage a community-based approach to banking. For those looking to move away from large national banks toward a more personalized experience, Addition Fi provides the tools to save, borrow, and invest in one place. Their ecosystem supports borrowers through various stages of life, from that first car loan to eventual retirement planning.
Pros:- Comprehensive suite of banking and investment services.
- Referral programs to help grow the community.
- Competitive rates for various products.
- Requires becoming a member to access all benefits.
6. GadCapital
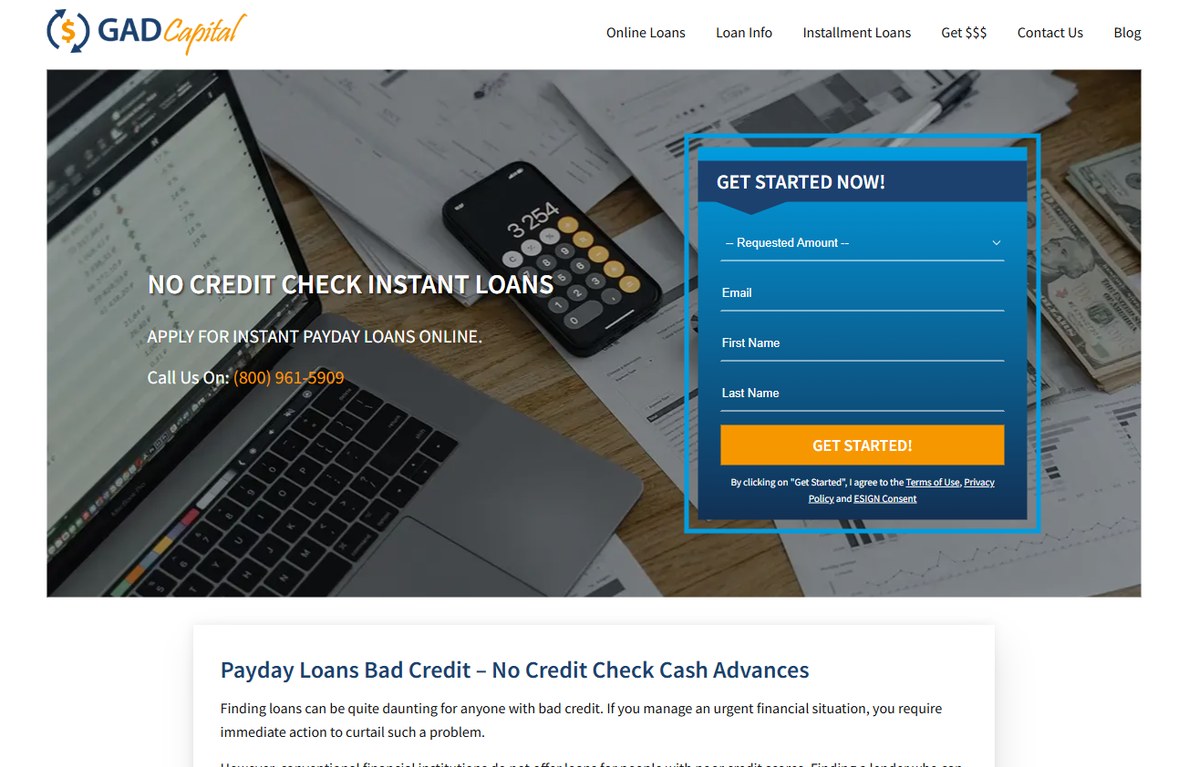
When the situation is dire and the clock is ticking, GadCapital is the “break glass in case of emergency” option. They specialize in online payday and installment loans for people with bad credit. They are designed for immediate action when conventional banks say no. This is a niche service for high-urgency situations where a standard three-day approval window is simply too long.
The platform allows for very small, quick loans, starting from as little as $100. If you are facing an urgent emergency—like a utility shut-off notice or an immediate medical co-pay—GadCapital is built to handle that pressure without a lengthy credit check. However, you must be extremely disciplined with repayment to avoid the compounding effects of high interest.
Pros:- No credit checks for certain loan types.
- Instant access to funds for urgent needs.
- Flexible amount ranges from $100 to $5,000+.
- Payday-style loans often come with very high costs.
- Risk of a debt cycle if not managed carefully.
Understanding the Total Cost of Borrowing
Many borrowers make the mistake of only looking at the monthly payment. For example, a $500 loan with a $50 monthly payment sounds affordable. But if that loan lasts for twelve months, you have paid $600 for a $500 loan. That is a 20% increase in cost. Always ask for the “Total Repayment Amount” before you sign anything. This figure tells you exactly how much cash will have left your pocket by the time the debt is settled.
You should also be aware of the difference between APR (Annual Percentage Rate) and the nominal interest rate. The APR includes not just the interest you pay, but also the fees associated with getting the loan, like origination or processing fees. If you are comparing two lenders, the one with the lower APR is almost always the better deal, even if the other has a lower stated interest rate but higher upfront fees.
Steps to Prepare for a Loan Application
To increase your chances of approval and secure the best terms, follow these three preparation steps:
- Audit Your Documents: Gather your most recent pay stubs, W-2 forms, and utility bills. Lenders want to see proof of residency and a consistent stream of income. Having these ready to upload can speed up your approval from days to minutes.
- Check for Errors: Free services like AnnualCreditReport.com allow you to see what is in your file. If there is a mistake—such as a debt that has already been paid being listed as active—dispute it immediately. A single error can be the difference between a 620 score and a 650 score.
- Calculate Your Debt-to-Income (DTI) Ratio: Add up all your monthly debt obligations, like rent, car payments, and credit card minimums, and divide that by your gross monthly income. Most lenders prefer a DTI below 36-43%. Knowing this number helps you understand how much more debt you can realistically afford.
Navigating the Loan Process
Before you sign your name, take a deep breath and look at the fine print. It is easy to get caught up in the excitement of an instant approval, but the total cost of the loan is what matters most in the end. Always check the APR, not just the monthly payment, to see the true cost of borrowing.
One common mistake is ignoring the impact of late payments. Even if a lender is willing to work with your bad credit, a single missed payment can act like a stone in your shoe, causing pain for years to come. Always ensure the monthly installment fits comfortably within your existing budget, leaving room for groceries and rent. A “buffer” in your budget is your best defense against future emergencies.
Another pitfall is the “quick fix” trap. While payday loans like those from GadCapital can save you from a crisis today, they can lead to a mountain of debt tomorrow if you aren’t careful. Use them sparingly and only for true emergencies. If you can, try to build towards more stable, long-term options like credit unions or personal loans from established firms. Building a history of on-time payments is the most effective way to climb out of a credit hole and achieve long-term financial freedom.