

The 7 Best Lenders for a Personal Loan After Bankruptcy in 2026
Last updated: 2026-10-16
Trying to fix your finances after a bankruptcy can feel like walking through a thick fog. You might need a quick car repair to get to work, or perhaps an unexpected medical bill popped up right after your discharge. Sometimes, it is just about bridging a gap caused by a sudden change in employment. The goal is to find a lender who sees your current potential instead of just your past mistakes.
The way people borrow money has changed a lot. Where a bankruptcy once acted as a permanent “no,” modern fintech companies and community institutions are looking at your recent behavior. They care about the trajectory of your finances today rather than just the scars left on your credit report from years ago. It is about where you are going, not just where you have been.
Picking the right lender involves more than just glancing at an interest rate. You have to weigh how fast you can get the cash, what the minimum requirements are, and how much flexibility the company offers. Some providers focus on rapid cash for emergencies, while others offer structured installment plans to help you rebuild your credit over time. It is a balancing act between speed and long-term stability.
Accessibility is a tricky term that does not mean the same thing to everyone. A lender that is incredibly easy to get approved with might charge a premium for that convenience. On the other hand, a lender with stricter rules might offer the lower rates you need for long-term debt management. You have to decide whether you need a quick fix or a long-term strategy.
- FastLendGo
- SoFi
- Prosper
- Avant
- Allegiance Credit Union
- VivaLoan
- World Finance
Evaluating Lenders for Post-Bankruptcy Borrowing
This ranking focuses heavily on how easy it is to get approved and how fast you see the money. Financial emergencies do not wait for a perfect credit score to resolve themselves. We prioritized lenders that provide clear paths for people with different credit histories. If a delay of three days means you lose your utility service, you need a lender that moves quickly.
We also looked at the variety of loan amounts available. A lender that only offers tiny microloans might not help if you need to consolidate debt or fix a roof. Conversely, traditional banks often have massive hurdles, requiring collateral or credit scores that a post-bankruptcy borrower simply cannot reach yet. We looked for “soft” credit pulls so you can shop around without hurting your score.
| Lender Name | Loan Amounts | Funding Speed | Credit Requirements |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Quick access | Bad/Fair/Good/Great |
| SoFi | see site | see site | see site |
| Prosper | $2,000 – $50,000 | Fast access | see site |
| Avant | see site | see site | see site |
| Allegiance Credit Union | see site | see site | see site |
| VivaLoan | $100 – $15,000 | As soon as tomorrow | All credit types welcome |
| World Finance | see site | see site | see site |
The Top Ranked Lenders for Rebuilding Credit
1. FastLendGo
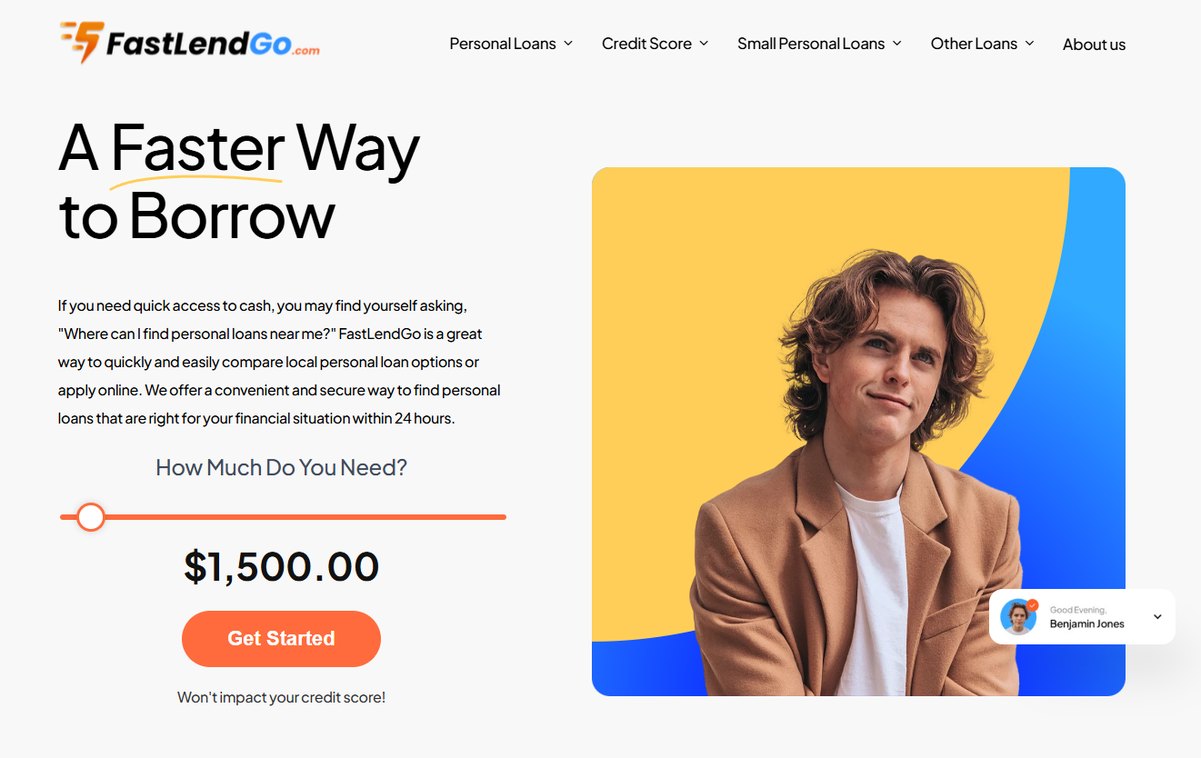
FastLendGo is a great option for anyone stuck in a tight spot. They offer a wide range of options, from small $500 loans to larger $5,000 packages. This flexibility is helpful if you are juggling several different needs, like a small repair for a car and a larger bill for your taxes.
The whole platform is built for speed, which is perfect if you need cash immediately. Whether you are dealing with dental bills, auto repairs, or home maintenance, they make it easy to compare local options. Traditional banks often require mountains of paperwork and multiple trips, but FastLendGo uses a digital-first approach to get things moving quickly.
It is a solid choice for a quick fix when you cannot afford to wait around for a long approval process.
Pros:- Wide variety of loan amounts from $500 to $5,000 and beyond.
- Covers specific needs like auto, dental, and roof financing.
- Accommodates various credit tiers from bad to great.
- May not offer the lowest rates for those with excellent credit.
2. SoFi
SoFi works more like a complete financial ecosystem. While many know them for banking and investments, they offer sophisticated tools to help manage your money. Their high-yield savings accounts can help you start rebuilding your savings effectively, giving you a safe place to park cash while your credit score climbs.
By automating your savings through their platform, you can build a buffer that helps you avoid high-interest debt in the future. This lender is perfect for the person who wants to manage everything in a single place, from checking accounts to mortgages.
They are more selective than the micro-lenders, but their products are built for people who have moved past their hardest financial struggles. It is a polished option if you are looking toward long-term stability and wealth growth.
Pros:- Integrated banking, investing, and insurance services.
- High APY options for savings accounts.
- User-friendly digital platform.
- Typically requires a higher credit tier for the best terms.
3. Prosper
Prosper gives you a look into peer-to-peer (P2P) lending. They provide substantial amounts, ranging from $2,000 up to $50,000. This makes them a heavy hitter if you need to tackle major debt or large expenses like tuition or home renovations. Because they rely on individual investors rather than a bank’s pool of money, their criteria can be different from traditional lenders.
Their platform is fast and secure. You can see your rates in about a minute through a soft credit pull. This is vital if you are worried about hurting your credit score while you are just shopping around for the best deal.
For anyone wanting to move away from standard bank loans, Prosper offers an efficient experience. It is a strong choice for large-scale financing when a traditional bank might have given you a hard no.
Pros:- High loan ceilings up to $50,000.
- Quick rate checking with minimal impact to credit.
- Fast and secure online application process.
- Peer-to-peer models can sometimes have variable approval rates based on investor demand.
4. Avant
Avant focuses on helping you move your financial life forward. They offer solutions like credit cards and installment loans, which are great for proving you can make consistent, on-time payments. Their approach feels more like a partnership, providing tools to help you reach specific goals like debt consolidation.
Whether you need to combine several high-interest payments into one manageable monthly bill or you just need an emergency loan for a sudden crisis, Avant has options. They aim to provide clear answers to difficult financial questions.
Their model is tuned for the middle-ground borrower. These are people who might not have elite scores but have shown steady income and responsibility through their recent financial history.
Pros:- Specializes in debt consolidation and emergency loans.
- Flexible solutions for different life stages.
- User-focused support and tools.
- Specific eligibility criteria can be difficult to navigate.
5. Allegiance Credit Union
Allegiance Credit Union is a community-focused institution that has been around since 1963. They operate under the idea that every story matters, including those of people rebuilding after a setback. This approach is different from large, impersonal national banks where you are just a number on a screen.
In a credit union, your local environment and your relationship with a loan officer actually carry weight. They offer products designed to help you save, borrow, and build a stronger future. If you prefer a mission-driven banking experience, a credit union is a refreshing change.
They often provide more personalized guidance during the application. This is incredibly helpful when you need to explain why your past bankruptcy is behind you and why your current situation is stable and looking up.
Pros:- Strong community roots and long-standing reputation.
- Mission-driven approach to member well-being.
- Diverse products for saving and borrowing.
- Geographic limitations may apply to membership.
6. VivaLoan
VivaLoan is built for speed. They offer loans starting as low as $100 up to $15,000. This wide spectrum lets you find exactly what you need, whether it is a tiny amount for new tires or a larger sum for a major life event. This flexibility is vital if you are still in the stabilization phase of your recovery.
One of their best features is the speed of funding. You can often receive your money as soon as the next business day. With a five-minute application process and an open policy for all credit types, they are a lifeline in an emergency.
While the ease of use is hard to beat, you should use these funds strategically. You want to avoid falling into a cycle of high-interest borrowing that can keep you stuck.
Pros:- Extremely fast funding, often by the next business day.
- Very low minimum loan amount of $100.
- Welcomes all credit types.
- High speed and accessibility can come with higher costs.
7. World Finance
World Finance is a specialized player in the market. They offer a variety of services, including retail and private banking. Their focus often leans toward more structured financial environments and specialized segments, providing options for people who do not fit into a standard consumer lending box.
This can include people with unconventional income streams or those needing very specific loan structures. They provide a deep look into both global and local economic trends for their clients.
For those seeking a more complex financial partner, they offer services that go beyond a simple personal loan. Their expertise is useful for borrowers navigating a sophisticated recovery involving multiple asset types.
Pros:- Wide breadth of financial services and insights.
- Expertise in diverse banking sectors.
- Professional focus on market trends.
- May be more complex than a standard consumer lender.
Strategies for Maximizing Your Approval Odds
Securing a loan after a bankruptcy discharge requires a strategic approach. Lenders want to see “stability indicators.” Even if your score is still recovering, you can improve your odds by providing organized documentation of your income. This means having recent pay stubs, bank statements, and tax returns ready to go. A lender is much more likely to say yes if they see a clear, unbroken line of income.
Another smart move is to consider a “secured” loan if “unsecured” options are proving too difficult. A secured loan is backed by an asset, like a car title or a savings account. Because the lender has collateral, their risk is much lower, which often leads to higher approval rates and better interest rates. Once you pay that loan back, your credit score usually gets a significant boost.
This path paves the way for the larger, unsecured loans you might need later on. It is a way to prove your reliability to the banks while you are still getting back on your feet.
Common Pitfalls to Avoid During Your Search
When you are looking for a loan, the biggest mistake is rushing into the first offer you see. You must compare the total cost of borrowing, not just the monthly payment. A low monthly payment can hide a much higher interest rate or a term that is so long you end up paying double what you borrowed. Always ask for the Annual Percentage Rate (APR) to see the true cost.
Another mistake is failing to check your credit report for errors before you apply. Even after a bankruptcy is discharged, mistakes can linger. A debt that was included in your bankruptcy might still show as “unpaid” on your report. Clean up your records first to give yourself the best chance of success.
Finally, read the fine print regarding prepayment penalties. Some lenders charge a fee if you try to pay the loan off early. This is the last thing you want when you are trying to move out of debt quickly. Approach your search with patience. The journey to financial health is a marathon, not a sprint.